Author: Adrien Feller

  • Altersvorsorgedepot 2027: Full Guide (Grants, Fees, Payout)

    Altersvorsorgedepot 2027: Full Guide (Grants, Fees, Payout)

    Altersvorsorgedepot 2027: the complete guide to Germany’s private pension reform

    Germany’s private pension reform is now law: the Bundestag passed it on 27 March 2026, and the Bundesrat gave its final approval on 8 May 2026. From 1 January 2027, a new state-subsidised retirement savings product enters the German market: the Altersvorsorgedepot (literally, “retirement provision depot”).

    This guide covers what you need to know, factually, before the market opens: who qualifies, how much the state contributes, what fees the law allows, and how you get your capital back at retirement.

    Why this reform?

    The product it replaces, the Riester-Rente, had a well-documented structural flaw: the capital guarantee requirement forced insurers and banks to park a growing share of savers’ money in low-yield bond instruments. In a world of persistently low interest rates followed by high inflation, that guarantee ended up costing more than it protected, crushing return potential over 20-to-40-year horizons.

    Lawmakers made a clear choice: instead of guaranteeing capital, the Altersvorsorgedepot relies on diversification and equity/ETF market exposure to build a genuinely competitive retirement pot, with no guarantee obligation attached.

    Existing Riester contracts are not disappearing. They carry grandfather protection (Bestandsschutz) and continue to run as before. Only new contracts opened from 2027 onward fall under the new regime. Transferring existing Riester savings into an Altersvorsorgedepot will also be possible, under conditions still to be specified by the implementing regulations.

    Who can open an Altersvorsorgedepot?

    This is one of the most significant changes in the reform: the pool of eligible savers is considerably wider than under Riester.

    Eligible for the state grant:

    • employees subject to the statutory pension insurance (gesetzliche Rentenversicherung);
    • civil servants (Beamte);
    • and, new under this reform, all self-employed individuals, including freelancers and independent professionals who don’t pay into the statutory pension scheme, a group previously excluded from Riester entirely.

    This matters a lot for many residents and international professionals in Germany working as freelancers or through their own company: unlike Riester, access to the grant no longer depends on compulsory statutory pension contributions.

    How much to save, how much the state pays

    Contribution thresholds

    • Minimum personal contribution required to qualify for the grant: €120 per year (€10/month).
    • Contribution level that unlocks the maximum grant: €1,800 per year.
    • Contributions remain possible up to €6,840 per year; beyond the €1,800 threshold, they no longer generate additional grants.

    The base grant (Grundzulage)

    • 50% grant on the first €360 paid in per year (up to €180);
    • 25% grant on the portion between €360.01 and €1,800 paid in per year (up to a further €360).

    For an annual savings effort of €1,800, the state therefore pays up to €540 in direct grants per year.

    Additional bonuses

    • Child bonus (Kinderzulage): up to €300 per child, per year.
    • Career-starter bonus (Berufseinsteigerbonus): a one-off bonus of roughly €200 for savers under 25 who open a contract.

    Taxation during the savings phase

    Contributions and grants qualify for a special-expenses deduction (Sonderausgabenabzug). The tax office automatically calculates whether the direct grant or the tax deduction is more favourable for the taxpayer, and applies whichever result is better. No tax applies to gains or reallocations made inside the depot during the savings phase.

    Fees are capped by law, a rare and important feature

    Another notable feature: the law imposes a statutory fee cap on the so-called “standard product”, the baseline offering every provider is legally required to make available.

    • The cap is set at 1% in effective annual costs (Effektivkosten) for this standard product, down from an initially proposed 1.5%.
    • This cap applies only to the standard product. More elaborate offerings, a wider fund selection, personalised advice, or managed strategies, sit within a broader fee range.
    • Pricing information published so far (as of July 2026) remains partial and indicative; final conditions won’t be known until closer to the January 2027 launch.

    Over a 30-to-40-year horizon, fee differences between market offers can amount to tens of thousands of euros in final capital. But the headline price is only part of the equation: a self-directed, execution-only account will mechanically show the lowest price, since no advice is included. A contract taken out with an advisor’s support, by contrast, includes an allocation tailored to your horizon and profile, optimisation of your grants, and, where relevant, coordination with your tax situation in another country: factors that also weigh on the final outcome, sometimes more than a fraction of a percentage point in fees. The right approach is to compare what’s actually included in the price, not just the number on the label.

    How and when you get your capital back

    The payout phase (Auszahlungsphase) follows precise rules:

    • Payouts can start no earlier than age 65.
    • Drawdown plan (Auszahlungsplan): capital stays invested and is withdrawn gradually; this plan cannot end before the saver’s 85th birthday.
    • Partial lump sum: up to 30% of the capital can be withdrawn as a single payment at the start of the payout phase, with the remainder paid out as a drawdown plan or a lifelong annuity.
    • Combining both options, for example, an initial partial lump sum followed by a drawdown plan, is explicitly allowed.
    • Taxation on payout: all amounts received (drawdown, annuity, or lump sum) are taxed as other income (sonstige Einkünfte) at the saver’s personal marginal tax rate, generally lower in retirement than during working life.

    One last thing before you compare offers

    From January 2027, the Altersvorsorgedepot will be sold by providers with different regulatory statuses: banks, insurance companies, and tied agents on one side; independent brokers on the other. The former can only offer products from their own house or designated partners; the latter, under German regulation (§ 34d or § 34f GewO), have no capital ties to product providers and can compare the entire market, effective fees, fund universe, and the quality of the payout structure.

    This distinction explains why two seemingly identical contracts can carry very different fees, within the limits of the statutory cap described above.

    Frequently asked questions

    Who can open an Altersvorsorgedepot? Employees paying into the statutory pension insurance, civil servants, and, new for 2027, all self-employed people and freelancers, even without compulsory statutory pension contributions.

    What’s the maximum grant I can receive? Up to €540 per year for a personal contribution of €1,800, plus up to €300 per dependent child and a one-off €200 bonus for savers under 25.

    Is there a legal fee cap? Yes, for the standard product every provider must offer: a maximum of 1% in effective annual costs. More elaborate products, outside the standard scope, can charge more.

    When and how can I access my capital? No earlier than age 65, as a drawdown plan (which cannot end before age 85), a partial lump-sum withdrawal (up to 30%), or a combination of both. Payouts are taxed at your personal marginal rate.

    Does my existing Riester contract disappear? No. Existing contracts continue to run under grandfather protection. Only new contracts opened from 2027 fall under the Altersvorsorgedepot. A voluntary transfer will be possible, under conditions still to be specified.

    When can I actually open one? The scheme takes effect on 1 January 2027. Exact conditions from individual providers are not all published yet as of July 2026.


  • Invest All at Once or Gradually: What the Data Actually Says

    Invest All at Once or Gradually: What the Data Actually Says

    Invest All at Once or Gradually: What the Data Actually Says

    The intuitive answer is usually wrong. Here’s why and when it’s right.

    You’ve just received a significant sum, an inheritance, a bonus, the proceeds from a property sale. And the question immediately follows: do I invest everything at once, or do I spread it out over several months to reduce risk?

    Most people’s instinct is to spread it out. It feels safer, more measured and it avoids the unsettling thought of having “put everything in” just before a market drop.

    That instinct is human. It’s understandable. And in most situations, it costs you money.

    Here’s why and in which specific cases spreading out remains the right call.

    I. The Two Strategies, Clearly Defined

    Lump Sum investing: you invest your entire available capital on day one. If you have €60,000, it goes in on 1 January, and the market does what it does with the full amount from that point forward.

    DCA (Dollar-Cost Averaging): you split your capital into equal instalments invested at regular intervals, for example, €10,000 on the 1st of each month for six months. The idea is that you don’t buy everything at the same price: if the market falls, the subsequent instalments are bought more cheaply.

    Neither approach is inherently right or wrong. Their relevance depends on context, asset class, and, we’ll come back to this, your actual psychological profile as an investor.

    II. What the Research Shows

    The reference study is Vanguard’s 2012 paper Dollar-Cost Averaging Just Means Taking Risk Later, which analysed thousands of 12-month historical periods across US, UK, and Australian markets going back to the 1920s.

    The main finding: investing in a lump sum outperforms dollar-cost averaging in approximately 66% of cases: two times out of three. The average performance difference is around 2.3 percentage points over 12 months.

    On a €100,000 capital base, 2.3% is €2,300 in a single year. Over 20 years, with the compounding effect (gains generating further gains), that gap becomes very difficult to close.

    This pattern holds across all time periods and all markets studied. It is not a statistical accident driven by one exceptional decade, it is a structural tendency.

    III. The Mechanics: Why Waiting Costs Money

    Over the past forty years, global equity markets have risen in approximately 63% of calendar months. In other words, if you pick a random month from recent history, there is a 6-in-10 chance the market went up that month.

    What this means in practice: when you decide to spread your investment over 6 months rather than investing immediately, you are statistically more likely to be buying at progressively higher prices than to be finding cheaper entry points. Spreading out is an implicit bet that the market will fall, a bet that has historically been wrong 63% of the time.

    Money on the sidelines is not neutral

    Capital waiting to be invested doesn’t work. Sitting in a current account or a money market fund, it earns little or nothing, while the market, most of the time, moves forward without it.

    On €60,000 spread over 6 months, half the capital waits an average of 3 months before being invested. If the market grows at 8% per year over that period, those 3 months of inactivity represent approximately €600 in missed performance, before even comparing the different purchase prices of each instalment.

    IV. The Numbers in Practice: A Simulation on Real Data

    Claire, 41, receives an inheritance of €60,000 in December and wants to invest it in an MSCI World ETF, an index fund that tracks the performance of approximately 1,500 large companies worldwide.

    She compares two scenarios over 6 months.

    The parameters:

    ParameterValue
    Available capital€60,000
    InstrumentMSCI World ETF
    Purchase price in December110.78
    Price on 1 June123.83
    DCA strategy€10,000 per month, over 6 months
    Purchase price in May (DCA)116.39 (5% more than in December)

    Results:

    StrategyInitial outlayValue in JuneGainReturn
    Invest everything in December€60,000€67,065+€7,065+11.78%
    Spread over 6 months (DCA)€60,000€66,244+€6,244+10.41%
    Difference+€821+1.37 pts

    Illustrative simulation on real data. Past performance is not indicative of future results.

    Over this rising period, investing in a lump sum generates €821 more. The reason is mechanical: the €60,000 benefits from market growth from day one. With DCA, the April, May, and June instalments are bought at progressively higher prices, the market didn’t wait.

    What if the market had fallen?

    Over a falling period, the gap reverses. DCA would have allowed the purchase of units at progressively lower prices, reducing the overall loss. But falling 6-month periods are statistically less frequent than rising ones, which is what the two-thirds figure in the Vanguard study reflects.

    V. When Spreading Out Is the Right Decision: Asset-by-Asset Analysis

    Asset typeRecommended approachWhy
    Equities and index funds (ETFs)Lump sumMarkets rise 2 times out of 3; every month of waiting has a cost
    Gold and commoditiesSpread gradually (DCA)High volatility, no holding income, price smoothing is relevant
    Real estate, REITs, SCPIsLump sumGenerates rental income from day one, every month of delay is a lost rent
    Private equity funds (ELTIFs)Determined by the fundThese funds call capital progressively, you don’t decide the timing

    Gold and commodities: when spreading makes sense

    Gold pays no dividend and generates no income while you hold it. Its value depends entirely on price movements in the market. Facing an asset this unpredictable, with no holding income, entering “all at once” at the wrong moment is offset by nothing. Here, gradual entry genuinely reduces that risk.

    Real estate and SCPIs: the rental income argument

    A SCPI unit, a collective property investment vehicle that distributes rental income to investors, generates income from the first day of ownership. At a net yield of 5% per year, €60,000 not invested for 6 months represents approximately €1,500 in rent you are deliberately forgoing.

    Private equity funds: when the structure decides

    ELTIFs and other private equity funds call your capital in tranches, in line with their own investment pace. You do not choose when to deploy, the fund manager decides. The DCA vs lump sum question generally does not apply here.

    VI. Investor Psychology: What Spreading Reveals and What It Costs

    Why our brains prefer spreading out

    Behavioural economists, most notably Daniel Kahneman, Nobel Prize in Economics, have shown that the pain felt from a loss is roughly 2.5 times more intense than the pleasure generated by an equivalent gain. In plain terms: losing €1,000 hurts psychologically far more than gaining €1,000 feels good.

    The result: if you invest €60,000 in one go and the market drops 10% the next day, seeing €6,000 “evaporate” in 24 hours triggers a strong emotional reaction, even if over 10 or 20 years it changes nothing about the final outcome. Spreading out protects against that immediate pain.

    The real cost of your psychological comfort

    Spreading out does not reduce your portfolio’s long-term risk. It trades slightly lower performance for better short-term psychological comfort. That is a conscious trade-off, not a risk-reduction strategy.

    A strategy held for 20 years is worth infinitely more than a mathematically optimal one abandoned in a moment of panic.

    The honest question to ask is therefore not “which strategy is better?” but: what is the real cost of my psychological comfort, and am I accepting it consciously?

    VII. How to Decide in Your Situation

    1. Do you actually have a lump sum available? If you are investing your monthly savings as they come in, DCA is not a choice, it is your reality. The question only arises when you have a single sum available all at once.

    2. What type of asset are you targeting? Refer to the table in Section V. For equities and index funds, the data leans clearly towards lump sum. For gold and no-income assets, gradual entry is more defensible.

    3. What is your real risk tolerance? Practical test: if your investments lose 20% of their value in the month following your purchase, how likely are you to sell? If that probability is high, spreading out is not an acceptable underperformance, it is a necessity for staying invested.

    4. Is a hybrid approach right for you? A middle-ground option exists: invest 60 to 70% immediately, and spread the remainder over 2 to 3 months. This structure captures most of the statistical advantage of lump sum investing while limiting full exposure to poor timing on the entire capital. For many investors, this is a pragmatic and psychologically sustainable compromise.

    Conclusion

    The DCA vs lump sum question has no universal answer, but it has structured ones. In equity markets, the data is clear: investing in one go outperforms two times out of three, and the difference compounds over time. In other asset classes, such as gold or commodities, the logic changes.

    What never changes is the underlying principle: a capital deployment decision deserves to be made with a clear understanding of its real implications, financial, psychological, and tailored to the specific nature of what you are buying.


    You’ve just received a sum to invest and you’re unsure of the best approach?

    The right strategy depends on your specific situation: your goals, your time horizon, your existing assets, your tax position, and your real psychological profile around risk. These are exactly the questions we work through together in an initial conversation.

    → Book a 30-minute discovery call


    This article is published for informational purposes only and does not constitute personalised investment advice. Any investment strategy requires prior examination of your individual situation in a dedicated consultation. Historical performance figures cited are not indicative of future results. Investing involves risk, including the risk of loss of capital.

  • When rents rise faster than salaries: do we really have to accept it?

    When rents rise faster than salaries: do we really have to accept it?

    Last week, I met up with an old university friend over coffee in Frankfurt. We had both moved to Germany from Belgium at roughly the same time, a little over five years ago. The conversation moved from our lives to our cities, and then, as it always does, to the subject of housing.

    She told me, with a touch of resignation: “Five years ago, it was clearly cheaper. Today, my rent makes up nearly a third of my salary.”

    I shared the feeling. But I wanted to test it against the numbers and, more importantly, draw some conclusions for the way I manage my own money.

    Rents in Germany’s major cities: one direction only

    I looked at ImmoScout24’s data on the five largest German metropolitan areas to see how average rents had moved between 2022 and 2026.

    Average price per m²BerlinHamburgFrankfurtMunichCologne
    Q1 2022€10.5€11.3€12.4€16.9€10.8
    Q1 2023€11.6€11.8€12.9€17.7€11.4
    Q1 2024€12.2€12.0€13.5€18.5€11.9
    Q1 2025€12.7€12.7€14.3€19.4€12.5
    Q1 2026€13.1€13.6€15.0€20.4€13.1
    Change+24.8%+20.4%+21.0%+20.7%+21.3%

    Source: ImmoScout24, average rents per m² for unfurnished housing, 2022-2026.

    The picture is unambiguous. Berlin, where my friend lives, has seen rents climb 24.8% in four years. None of the major cities has been spared: every one of them shows growth between 20% and 25%. Munich, already at the top of the table in 2022, continues to climb. Cologne, often perceived as more affordable, in fact follows the same trajectory as Berlin. Whichever city you look at, between 2022 and 2026, rents have moved in only one direction: upward.

    The silent erosion of savings

    The direct cause is well known: too few homes are being built, too slowly, against a demand that simply isn’t easing in the cities. But behind this rent inflation, another force is at work in parallel, one that affects every household, tenant or owner: inflation itself. Its most damaging effect doesn’t fall on what we consume, but on the money that sits idle in a bank account.

    A concrete illustration: €100,000 left in a current account in 2016 today buys you the equivalent of only €79,000, once cumulative German inflation over ten years is taken into account. What looked like a cautious approach has, in reality, meant a loss of more than 20% of purchasing power over the decade.

    This is the double dynamic that weighs on households: the cost of living rises, and at the same time, the savings meant to protect against it lose value year after year.

    Source: Statista – Average inflation rate Germany.

    A shift in perspective

    At the café, my friend asked me the question most people eventually ask:

    “So, what are you actually doing about it?”

    I answered with a question of my own:

    “If rents are rising for tenants… who are they rising for, at the other end of the chain?”

    Her answer came quickly: “For the landlords.”

    Exactly. What most people experience as a constraint, the steady rise in rents, represents, for those who own rental property, a stream of income that grows at the same pace. The difficulty is well known: buying an apartment in Berlin, Frankfurt or Munich today requires several hundred thousand euros, a sizeable mortgage, and concentrates the entire risk on a single apartment, a single tenant, a single city.

    There is, however, a third path, distinct both from being a tenant and from buying property directly.

    Investing in real estate without buying an apartment

    The principle is straightforward: rather than buying a property yourself, you subscribe to shares in a company that owns a portfolio of buildings, between 10 and 20 properties, mixing residential, office and retail, spread across several European countries. The rental income collected by the company is then passed on to investors, in proportion to the number of shares they hold.

    The investor’s position is fundamentally different from owning an apartment outright. Property management, maintenance, tenant search and any necessary works are all handled by the company. The risk is no longer concentrated on a single apartment, but spread across the entire portfolio, in several countries and across many tenants. And the entry threshold starts at just €1000, making this type of investment accessible long before one has saved enough for a direct purchase.

    An important distinction from German real estate funds

    Many readers in Germany will remember the difficulties of the offene Immobilienfonds (open-ended real estate funds) in the late 2000s, when several of them suspended redemptions before being wound down at a loss. The investment discussed here differs from those funds in three important respects.

    First, its legal structure. The investor directly owns shares in a property-holding company, not units in a collective fund. The rules governing how it operates, how it is valued, and how it invests are different.

    Second, the way money is recovered. Withdrawals don’t depend on the immediate cash position of the company; they rely on the resale of shares to new investors. This requires a longer investment horizon, but it avoids the scenario of a generalised freeze on withdrawals during periods of market stress.

    Third, its track record. This format has existed since the 1960s and has been through several very different real estate cycles, including the 2008 crisis. It is used today by several hundred thousand savers across Europe.

    What it pays, and how the fees work

    In financial terms, this type of investment has historically returned around 7% per year before fees, or roughly 6% per year once management fees are deducted. In some years, the value of the share itself also rises, depending on the underlying property market. It is worth bearing in mind that what has been observed in the past is no guarantee of what will happen in the future, and the value of the shares can also decline.

    The fee structure deserves a brief note. Subscription fees are already included in the share price and are only effectively borne at the time of resale. In practical terms, as long as the investor holds the shares, the recommended duration is at least 5 to 7 years, these fees do not reduce the income received each year. Management fees are taken directly by the company from the rents it collects, before they are passed on to investors. The investor’s only obligation is to declare the income received on their tax return, as with any other rental income.

    This type of investment has a name in France: SCPI: Société Civile de Placement Immobilier, a regulated French real estate investment vehicle.

    Bear it, or benefit from it

    The day after our conversation, my friend wrote to ask for a meeting. She wanted to look at this type of investment in detail, and to understand whether it could fit her own situation.

    That is exactly the right question. An SCPI is not a universal solution. Whether it makes sense depends on how long you can leave your money invested, how much capital you have available, your personal objectives, and your tax situation. This is the approach I take at Feller Financial Advisory: looking at a situation as a whole before considering any recommendation.

    Rising rents, the erosion of savings, inflation: these are forces no one can bend on their own. But the choice between bearing them and benefiting from them, that one is yours to make.

    If you would like to explore the second option, let’s take 30 minutes together. We will look concretely at whether, and how, this type of investment could fit your situation.


    This article is published for informational purposes only and does not constitute personalised investment advice. Any recommendation requires a prior review of the investor’s individual situation in a dedicated meeting. The performance figures mentioned are historical and are no guarantee of future returns. An SCPI investment carries a risk of capital loss; the value of the shares and the income distributed can move both upward and downward. The resale of shares is not guaranteed and depends on demand from investors on the secondary market. The recommended investment horizon is at least 5 to 7 years.

  • bAV Germany: The 2026 Guide to Company Pensions

    bAV Germany: The 2026 Guide to Company Pensions

    The German Company Pension Scheme (bAV): Practical Guide 2026

    Understand, optimize, and secure your company pension, with calculation examples, comparisons, and concrete strategies.


    Table of Contents

    1. What is the bAV?
    2. The Leverage Effect of the Employer Match
    3. Taxation During the Accumulation and Payout Phases
    4. The 5 Investment Vehicles (Durchführungswege)
    5. The 3 Pillars: Finding a Balance
    6. Job Changes and Key Pitfalls
    7. Conclusion

    01. What is the bAV?

    The German Pension System: The 3 Pillars

    In Germany, old-age provision officially rests on three complementary pillars. Understanding this architecture is essential to grasp the exact role the bAV plays in your retirement strategy.

    PillarNameFinancingLevel of Coverage
    1st PillarStatutory Pension (GRV)Mandatory contributions employer/employee (50/50)< 50% of average income (declining)
    2nd PillarCompany Pension Scheme (bAV)Employee ± employer matchVariable (depending on contract)
    3rd PillarPrivate Provision (ETF, Real Estate, etc.)Employee aloneVariable, unlimited

    The Principle of Deferred Compensation (Entgeltumwandlung)

    The bAV is based on a simple mechanism: Instead of receiving a portion of your gross salary in cash, you instruct your employer to pay this amount directly into a retirement contract. This amount is deducted before taxes and, up to a certain limit, before social security contributions.

    The Legal Maximum Limits for 2026

    Type of ExemptionMonthly LimitAnnual LimitCalculation Basis
    Tax Exemption (Income Tax)676 €8 112 €8 % BBG (101 400 €)
    Social Security Exemption338 €4 056 €4 % BBG (101 400 €)
    Tax-Free Only Zone (338 € to 676 €)338 €4 056 €No exemption from social security

    (BBG = Beitragsbemessungsgrenze / Contribution Assessment Ceiling of the statutory pension insurance for 2026).

    Practical Tip: Check whether you are affiliated with the statutory health insurance (GKV). If you are privately insured (PKV), the limits for social security exemption apply differently.

    02. The Leverage Effect of the Employer Match

    Practical Example: Thomas, Employee in Munich, €65,000 Gross/Year

    Thomas (35 years old), an engineer at a Bavarian mid-sized company, wants to evaluate the real impact of a bAV contribution of €200/month. His employer offers a 30% match. His marginal tax rate is estimated at 36%. Here is what actually happens:

    ElementWithout bAVWith bAV (€200/month)Impact
    Gross Salary (monthly)5 417 €5 217 €-200 €
    Social Security (~21.75%)-1 178 €-1 134 €+44 €
    Estimated Taxable Income4 239 €4 083 €-156 €
    Income Tax-898 €-837 €+61 €
    Net Salary3 341 €3 246 €-95 €
    Capital Invested in Contract260 € (incl. 30 % match)+260 €

    Result: Thomas gives up €95 net, but €260 flows into his contract. The immediate leverage effect is more than 2.5x even before any financial return.

    The Break-Even Point: Why Demand 30%?

    The statutory minimum employer match is 15% (mandatory for all deferred compensation contracts since 2022). But beware: This is not a gift from the employer, but the passing on of the social security contributions the company saves. Furthermore, this 15% often just barely covers the insurance costs and does not compensate for the loss of pension points in the statutory pension (Gesetzliche Rente).

    For a bAV contract to beat a private investment in the financial markets, a higher employer contribution is required. Experts agree that the bAV becomes truly advantageous starting at a match of 30%. The following table illustrates this (simulation over 25 years at a 3% annual return in the bAV).

    Employer MatchInvested Capital/MonthbAV Capital (Gross after
    25 yrs at 3%)
    Actual bAV Value (Estimated NET after taxes)Required Savings Rate (at 6%) to match this Net
    0 %200 €89 201 €≈ 66 900 €~ 96 €
    15 %230 €102 581 €≈ 76 900 €~ 111 €
    30 %260 €115 962 €≈ 86 900 €~ 125 €
    50 %300 €133 802 €≈ 100 300 €~ 145 €

    The column ‘Required Savings Rate‘ indicates the amount you would need to invest out of pocket every month into a private investment (e.g., an ETF/Fund at 6% p.a.) to achieve the same net capital.

    How to Evaluate Your Employer’s Offer?

    The percentage of the employer match is the main criterion for judging whether a bAV contract is worthwhile:

    • 0 % : The initial tax savings are neutralized by deferred taxation in retirement and the insurer’s fees. Ultimately, this yields no more than a private investment, but carries the major disadvantage of locking up your money until age 62.
    • 15 % : This statutory minimum gives you only a slight mathematical advantage over a private investment (equivalent to about €16 of additional profit per month). You have to weigh whether this small bonus justifies locking away your money for decades.
    • 30 % : From this level onwards, the employer’s assistance generously covers all future taxes and fees. By paying €95 out of pocket, you get the same value as if you had saved €125 privately. Locking up the capital until retirement becomes highly attractive here.
    • 50 % (and more): With such strong support, your employer finances a large part of your future pension. Your personal savings effort is leveraged so heavily that this contract becomes far more advantageous than almost any traditional private investment.

    03. Taxation During the Accumulation and Payout Phases

    Phase 1) During the Accumulation Phase: The Immediate Tax Advantage

    During the build-up phase, contributions are, as mentioned above, exempt from income tax (up to 8% of the BBG) and social security contributions (up to 4% of the BBG).

    Phase 2) In Retirement: Deferred Taxation (nachgelagerte Besteuerung)

    The benefits from the bAV are fully taxable upon payout. Three types of deductions apply:

    DeductionEstimated RateCalculation BasisNote
    Income Tax (ESt)Marginal tax rate in retirement (often 20–30%)Entire pension or capitalThe tax rate in retirement is usually lower than during working life.
    Health Insurance (KV)~14.6% + Additional Contribution (Total ~16-17%)Only on the portion exceeding €197.75/month (Freibetrag)Applies only to statutory insured (GKV). Privately insured (PKV) do not pay KV/PV on the bAV. The allowance (Freibetrag) protects the first €197.75.
    Long-Term Care Insurance (PV)~3.4% to 4% (depending on children)On the entire pension if it exceeds €197.75/month (Freigrenze)No deduction if the limit is exceeded; full contributions apply from the first euro. Applies only in GKV.
    Solidarity Surcharge (Soli)5.5% of Income TaxCalculated Income TaxFull exemption if the annual income tax due is below €20,350 (single) or €40,700 (married). Exempts the vast majority of retirees.

    Calculation Example: Monthly bAV Pension of €400 (GKV Member)

    Thanks to the statutory allowance of €197.75 in 2026, health insurance is only due on the exceeding amount:

    • Gross Pension : 400 €
    • Income Tax (estimated 22%) : -88 €
    • Health Insurance (KV ~ 16.3%): – 33 € (Thanks to the allowance, applies only to the difference: €400 – €197.75 = €202.25)
    • Long-Term Care Insurance (PV ~ 3.4%) : – 14 € (Calculated on the full €400, since the pension exceeds the exemption limit of €197.75)
    • Net Pension Paid Out: 265 € (equivalent to approx. 66% of the gross amount)

    A retiree with private health insurance (PKV) bypasses the KV/PV contributions; their net pension in this example would be approx. €312.

    04. The 5 Investment Vehicles (Durchführungswege)

    Unlike a private savings plan where you freely choose your bank, with the bAV, the company decides on the provider and the legal framework (Durchführungsweg). There are five options:

    • Direct Insurance (Direktversicherung): The absolute standard and the most widespread vehicle. The employer takes out a classic life or pension insurance policy on your behalf. This option is the easiest to transfer when changing jobs.
    • Pension Fund (Pensionskasse): A legally independent pension institution, often for specific industries. Returns are moderate but very stable, a good choice for employees who plan to stay with the same company long-term.
    • Pension Fund (Pensionsfonds): The most dynamic option. It allows for a higher exposure to the stock market to boost returns, though it entails higher volatility. Particularly suitable for employees with a long investment horizon.
    • Support Fund (Unterstützungskasse): The preferred instrument for executives and high earners. The main advantage: There are no legal maximum limits for contributions, meaning far higher amounts can be deferred tax-free than with standard vehicles.
    • Direct Commitment (Direktzusage / Pensionszusage): The most binding model for the company, which provisions your future pension directly as a liability on its own balance sheet. Offers maximum tax advantages but is mostly reserved for large companies and managing directors.

    05. The 3 Pillars: Finding a Balance

    Where does the bAV fit into your overall strategy?

    The bAV should not be viewed in isolation: Its full value only becomes apparent when compared to the other two pillars. Each has its own strengths and limitations.

    Criterion1st Pillar: Statutory Pension2nd Pillar: bAV3rd Pillar: Private Provision
    FinancingMandatory contributions employer/employeeDeferred compensation & employer matchVoluntary individual effort
    Tax AdvantageDeductible up to €30,826/yearTax-free up to €676/month, SS-free up to €338/monthDepends on the product (Riester, Rürup, Brokerage…)
    Expected ReturnLinked to wage growth and demographics1.5% – >5% depending on investmentVariable depending on asset allocation
    LiquidityNone (Payout from age 63–67)None (Payout from age 62)Completely flexible (except Rürup/Riester)
    Level of Coverage< 50% of average income (declining)Variable addition based on personal contributionUnlimited, depends on savings rate

    Important: No pillar can stand alone. The first forms the guaranteed foundation, the bAV optimizes this through tax advantages and employer subsidies, and the third pillar provides the absolute flexibility that the other two lack. It is their interplay that makes your strategy robust.

    06. Job Changes and Key Pitfalls

    What happens if I change employers?

    ScenarioLegal BasisWhat happens?Recommendation
    Transfer to the new employerLegal right to capital transferThe capital moves to the new bAV. Warning: The new insurer often charges new acquisition costs.Carefully compare costs before transferring.
    Pausing Contributions (Beitragsfreistellung)Absolute legal right (§ 1a BetrAVG).The contract is “frozen.” You stop paying in, but the existing capital continues to grow until retirement.When changing jobs, this is very often the best option to avoid paying commission fees twice.
    Early Payout (Abfindung)Prohibited before age 62Since the Company Pension Strengthening Act II (2026), the employer may pay out the contract without your consent if its value is below €7,119.The paid-out capital will be heavily taxed by income tax in that year.

    Vesting: When do the employer contributions truly belong to you?

    Since 2018, the rights to employer contributions are legally vested (Unverfallbarkeit) as soon as the contract has existed for 3 years and you have reached the age of 21. If you leave the company before that, you may lose the accumulated match.

    ⚠ Warning: Never sign a bAV transfer into a new contract without comparing the acquisition and distribution costs. A contract with a 4% acquisition fee can wipe out several years of tax benefits.

    07. Conclusion

    The bAV is a precise instrument: Poorly configured, it disappoints; optimally adjusted, it shines. Before signing the offer from your HR department or making a decision during a job change, a strict review is essential:

    1. The Employer Match: Is it above the 30% threshold? If not, a detailed mathematical analysis is strictly required.

    2. Cost Analysis: A contract with a 4% acquisition fee eats up your tax advantages. Examine the provider’s cost structure closely.

    3. Choice of Investment Vehicle: Does the proposed model (usually Direct Insurance) truly fit your tax bracket and investment horizon?

    4. The Pension Gap: Use the projections from the German Statutory Pension Insurance to calculate the impact of deferred compensation on your state pension.

    5. GKV vs. PKV: Take into account the massive impact your health insurance status will have on the later net return of your bAV.

    6. Pension vs. Capital Payout: Does your contract offer a flexible payout? It is important to compare the tax consequences of both scenarios in advance.

    7. Your Overall Asset Allocation: No contract replaces a liquid financial cushion. Balance your savings rate between the locked-in bAV and freely available private investments.

    Let us analyze your contract

    The bAV is an extremely powerful tool, provided it is set up correctly. An independent review of your contract ensures that the match is sufficient, no hidden costs are lurking, the right investment vehicle was chosen, and taxation in old age is optimized.

    Contact us for a personalized analysis of your individual situation.


    Disclaimer: This practical guide is for informational and educational purposes only and does not constitute personalized financial advice. All figures and exemption limits are based on the applicable German legislation of the year 2026. Consult an independent advisor for an analysis tailored to your personal situation.

  • The €668k Cost of Early Retirement in Germany for Executives

    The €668k Cost of Early Retirement in Germany for Executives

    The cost of time: understanding the €668,000 opportunity cost of early retirement in Germany

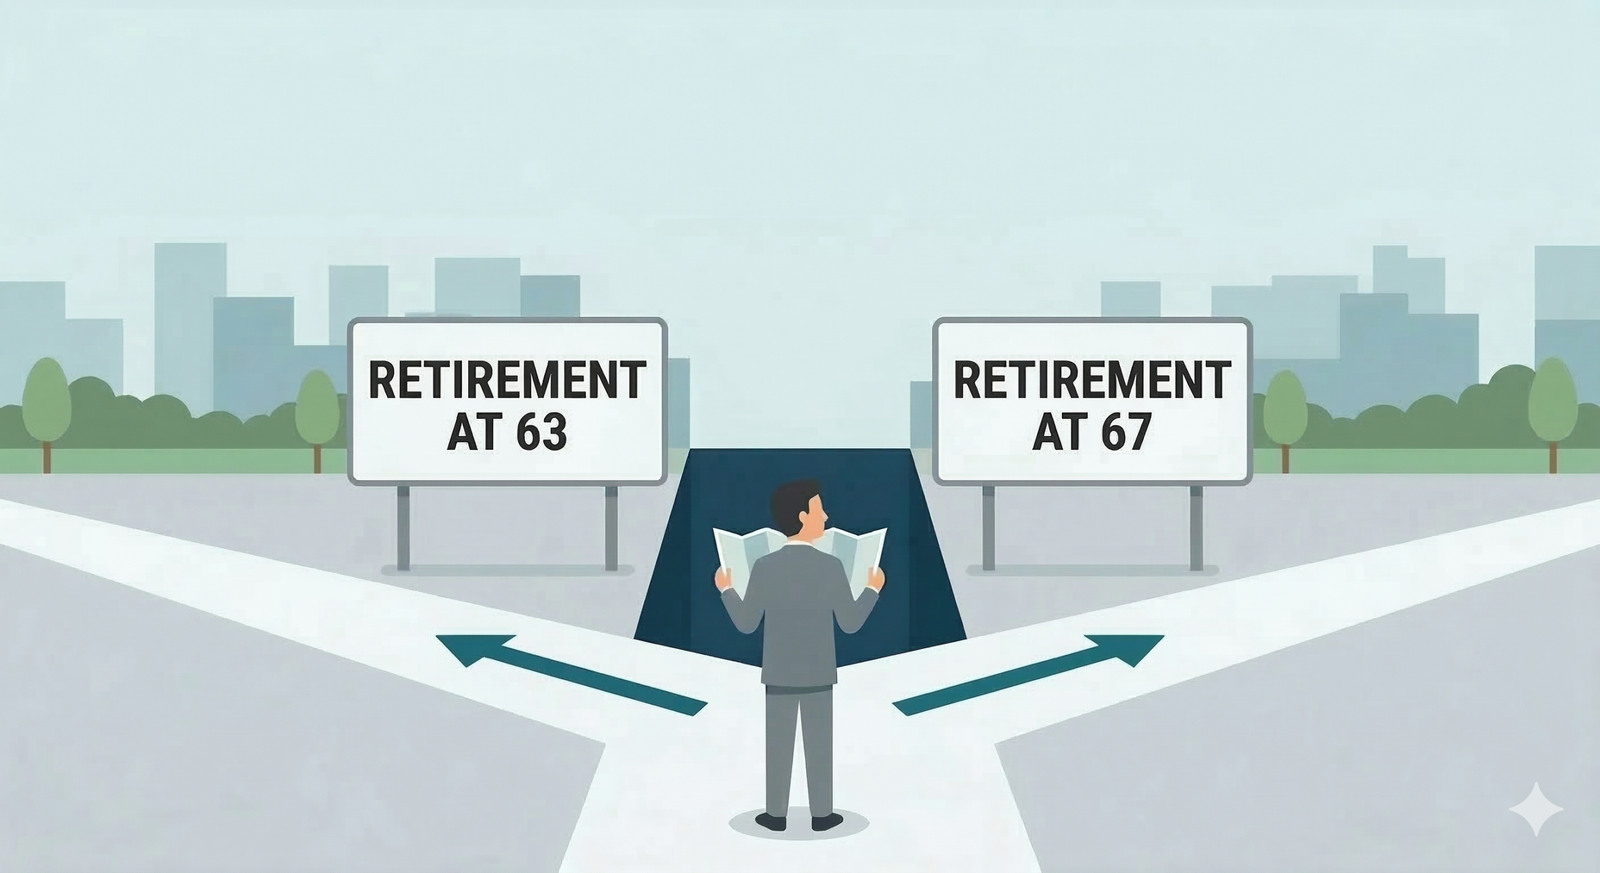
    For corporate executives and high-net-worth professionals in Germany, the decision to retire at 63 is rarely driven by financial necessity. It is a prioritisation of temporal autonomy. The Rente mit 63 is a well-established social concept, but executing this transition without a precise, well-thought financial architecture exposes the individual to a significant, often unrecognised, capital reduction.

    As the German state manages a shifting demographic landscape, specifically, the narrowing ratio of active contributors to beneficiaries, the Deutsche Rentenversicherung relies on the principle of actuarial neutrality. The statutory system is structurally designed to penalise early exits to ensure the state’s long-term liabilities remain balanced.

    For the affluent professional, retiring at 63 without a bespoke mitigation strategy triggers a compounding reduction in lifetime wealth that our models place at ~€668,000. This article aims to precise how this wealth reduction arises.

    I. The mechanics of the state pension

    The German statutory pension is not a percentage of your final salary. It is a defined-contribution system denominated in a proprietary currency: the Entgeltpunkt (pension point / EP). Every year, your annual gross salary is divided by a benchmark salary, giving you a defined amoutn of pension points.

    Your gross monthly pension is determined by four variables: your lifetime accumulated points (Entgeltpunkte), multiplied by the access factor (Zugangsfaktor), the pension type factor (Rentenartfaktor), and the current monetary value of a single point (Aktueller Rentenwert).

    For high earners, point accumulation is constrained by two statutory ceilings:

    Parameter2026 ValueImplication
    Durchschnittsentgelt (average benchmark)€51,944Earning this yields exactly 1.00 EP per year
    Beitragsbemessungsgrenze (contribution ceiling)€101,400Income above this is invisible to the system
    Maximum annual accumulation1.95 EP (€101,400/€51,944)Absolute ceiling
    Aktueller Rentenwert (point value, Jan 2026)€40.79Rising to €42.52 from July 2026

    Income above €101,400 generates no additional pension entitlement whatsoever. The pension does not scale with professional success beyond this ceiling and this constraint, combined with the penalty mechanism described below, is where the actuarial mathematics begin to work decisively against the early retiree.

    II. The executive trajectory: a quantitative case study

    To illustrate the financial impact, we analyse “Alex,” a 40-year-old senior executive. His career trajectory maps as follows: he entered the workforce at 25 and has accumulated 15 points over his first fifteen years (earning the benchmark salary on average). Between ages 40 and 55, he averages 1.5 points per year adding 22.5 points to reach a total of 37.5 by age 55. After 55, with gross income exceeding €10,000 per month, he hits the statutory ceiling and earns the maximum 1.95 points annually.

    At 55, Alex has two possibilities:

    MetricScenario A: Retire at 63Scenario B: Retire at 67
    Remaining active years (from age 55)8 years12 years
    Points yield in final phase15.6 (8 × 1.95)23.4 (12 × 1.95)
    Total lifetime accumulation53.1 points60.9 points
    Zugangsfaktor (access factor)0.856 (permanent 14.4% penalty)1.000 (no penalty)

    III. Projecting the financial reality: the €1,075 monthly gap

    To understand what each scenario actually delivers, we project the Aktueller Rentenwert (value of one pension point) forward at a conservative 2% annual growth rate consistent with its historical wage-indexation trajectory. Starting from the January 2026 baseline of €40.79, the point value reaches approximately €64.32 by the time Alex turns 63 (in 23 years), and €69.62 by 67 (in 27 years).

    Applying these projected values to each scenario:

    • Scenario A: 53.1 points × €64.32 × 0.856 = €2,923 gross per month at age 63
    • Scenario B: 60.9 points × €69.62 × 1.000 = €4,239 gross per month at age 67

    To compare both scenarios at the same age, we apply 2% annual indexation to Alex’s early pension from 63 to 67. By age 67, his Scenario A pension will have grown to approximately €3,164 per month. Against Scenario B’s starting pension of €4,239, the result is a permanent structural shortfall of €1,075 every single month.

    Crucially, this gap is not static. Because both pensions are indexed at the same rate, the euro-value of the shortfall increases over time. By age 87, the monthly deficit will have widened to nearly €1,597. This is the compounding nature of the actuarial penalty and the reason a single snapshot figure understates the true lifetime exposure.

    IV. The triple penalty: anatomy of the €668,137 gap

    Assuming a life expectancy to age 87, three mechanisms operate independently and in parallel. This analysis is conducted gross-to-gross throughout, excluding individual tax assumptions, to ensure the figures are transparent and auditable regardless of personal marginal rate.

    1. The gross transition deficit (ages 63 to 67)

    Between ages 63 and 67, Alex stops earning his peak salary of €10,000 gross per month, forfeiting €480,000 in gross income over four years. During this same period, he collects his early pension, approximately €144,602 gross over those 48 months. The direct gross cash flow deficit during this transition is €335,398.

    2. The forfeiture of peak points (ages 67 to 87)

    By stopping at 63, Alex permanently forgoes 7.8 points: those that would have been earned in the final four years at the maximum accumulation rate. These are mathematically the most valuable points of his career, contributing disproportionately to his total lifetime accumulation compared to his earlier working years. Projected over a 20-year retirement with 2% annual indexation, their absence costs €168,024 in gross pension income.

    3. The contagion effect (ages 67 to 87)

    The Zugangsfaktor mandates a 0.3% deduction for every month of early retirement. At 48 months, this produces a 14.4% permanent discount, applied not to the missing points alone, but retroactively to every point Alex has ever accumulated, from the first day of his first job. Over 20 years of retirement, this additional drag costs €164,715 in gross pension income.

    Source of erosionDriverGross impact
    Transition deficit (ages 63–67)€480,000 foregone salary minus €144,602 pension collected€335,398
    Missing peak points (ages 67–87)7.8 forfeited points × indexed point value€168,024
    Early-retirement discount (ages 67–87)14.4% permanent ZF penalty on 53.1 accumulated points€164,715
    Total lifetime wealth reduction€668,137

    Executing an early retirement without an offsetting capital strategy represents a substantial, unrecoverable reduction in lifetime wealth.

    V. The three headwinds your pension letter does not mention

    The standard annual Renteninformation from the Deutsche Rentenversicherung is designed for average earners in straightforward circumstances. For the high-net-worth professional, it is dangerously incomplete. Three structural complexities are systematically absent from every public planning tool.

    The first is the hidden offset mechanism. The standard statement clearly outlines the permanent penalty for early retirement, but it fails to mention your statutory right to erase it. Starting at age 50, you can make voluntary payments (Ausgleichszahlungen) to “buy back” these missing points. For high earners, spreading these contributions across peak-earning years generates substantial tax deductions. This allows you to effectively use current tax savings to help fund your early exit, a major strategic advantage that generic projections completely ignore.

    The second is healthcare friction. Early retirement fundamentally restructures how health insurance premiums are calculated and subsidised, whether you hold private insurance (PKV) or voluntary statutory coverage (freiwillig GKV). The transition to retirement changes your premium basis in ways that can consume your net monthly liquidity. A silent drag compounding over a multi-decade retirement horizon.

    The third is the inflation illusion. The statutory pension is indexed to average wages, not to your personal cost of living. If your bridge capital is allocated to conservative, low-yield instruments, its real purchasing power will erode materially before age 70. Any credible bridge strategy must be engineered to outpace both headline inflation and the natural spending drift of a high-expenditure retirement.

    Bridging a gap of this magnitude requires a structured financial plan, not generic savings advice. The solution typically focuses on funding tax-advantaged private pensions and building inflation-resistant income streams such as real estate to replace your lost salary. How and which of these instruments are combined depends entirely on your tax situation, your existing portfolio, and your personal timeline.

    Conclusion: engineering your exit

    Germany’s statutory system rewards patience and taxes impatience at scale. For the successful professional, however, trading capital for time is often the ultimate objective and it is entirely achievable when the structural groundwork is laid in advance.

    The question is not whether you can afford to retire at 63. It is whether you know the euro-precise magnitude of your personal exposure, and whether the mechanisms necessary to neutralise it are already in motion this fiscal year.

    Every executive’s financial architecture is unique, governed by specific tax situations, existing asset allocations, and long-term legacy goals. Standardised advice leaves substantial capital exposed to structural inefficiencies that compound silently over decades.

  • 2026 Fiscal Changes: Strategic Guide for High-Earning Professionals

    2026 Fiscal Changes: Strategic Guide for High-Earning Professionals

    2026 Fiscal Changes: Strategic Guide for High-Earning Professionals

    Your Net Pay Is Under Pressure

    If you earn above €100,000, 2026 marks a critical inflection point. For the first time, the pension insurance contribution ceiling has broken the six-figure barrier, reaching €101,400. Combined with slower growth in tax relief, this creates a “fiscal squeeze” where your salary increases are being absorbed by rising social contributions faster than tax breaks can offset them.

    Social contribution ceilings are growing at 5%+ while your basic tax allowance increases by only 2.08%. This gap means less take-home pay relative to your gross salary, even if you receive a raise.

    The Numbers That Matter to You

    Metric20252026Change
    Health Ceiling (GKV)€66,150€69,750+5.44%
    Pension Ceiling (RV)€96,600€101,400+4.97%
    Compulsory Insurance Limit€73,800€77,400+4.88%
    Basic Tax Allowance€12,096€12,348+2.08%
    Kindergeld (Monthly)€255€259+1.57%

    Key Insight: The pension ceiling grew by €4,800, while your tax-free allowance only increased by €252. For families, Kindergeld rose by just €4/month per child. The state’s claim on your income is expanding far faster than the relief mechanisms designed to offset it.

    Scenario Analysis: A €105,000 Earner in 2026

    Let us examine a concrete example to understand the real impact:

    You earned €105,000 in 2025 and receive a 3% raise to €108,150 in 2026.

    What Happens to Your Additional €3,150?

    1. Social Contributions Expand: Because the pension ceiling rose from €96,600 to €101,400, an additional €4,800 of your income is now subject to the full 18.6% pension contribution (9.3% employee share). For an employee, this means an extra €446.40 in deductions per year, or approximately €37.20 per month.
    2. Tax Relief Barely Moves: Your basic allowance increased by only €252 annually (€21/month). This provides a minimal offset against higher contributions.
    3. Net Result: Your 3% gross raise yields significantly less than 3% in net terms. The expansion of contribution ceilings captures a disproportionate share of your increase.

    For high earners, 2026 salary increases are being systematically diluted by faster-growing social obligations.

    The €100,000 Milestone: Why It Matters

    Breaking the €100,000 pension ceiling is not just symbolic, it represents a fundamental expansion of the state’s access to your income.

    Before 2026:

    • Income above €96,600 was exempt from pension contributions
    • This created a “protected zone” for high earners

    From 2026:

    • That protected zone shrinks by €4,800
    • Maximum annual pension contributions rise from approximately €8,985 to €9,430 (employee share)
    • Employers face identical increases, affecting total compensation budgets

    For professionals earning €150,000+: While your income above €101,400 remains contribution-free, the ceiling expansion means you are paying maximum contributions on a larger base. Combined with marginal tax rates of 42%+ in this bracket, your effective take-home percentage continues to compress.

    Retirement Planning Implications

    These changes directly impact your long-term wealth accumulation strategy:

    Pension System Sustainability Concerns

    The government is raising contribution ceilings not to build surpluses, but to patch deficits. Some facts:

    • Projected 2026 deficit: €9.7 billion
    • Sustainability reserve: Expected to drop to €32.4 billion (just one month of expenditures)
    • Emergency measure: Minimum reserve requirement raised from 0.2 to 0.3 monthly expenditures, funded entirely by your contributions

    You are paying more into a system that is operating closer to its liquidity floor, not building long-term security.

    The 48% “Stability Line” Promise

    The government pledges to maintain pension levels at 48% of average wages through 2031. The cost? An additional €10 billion annually by 2031, requiring either:

    • Further contribution rate increases
    • Higher ceilings
    • Federal budget subsidies (which are politically vulnerable to cuts)

    Future contribution rates are more likely to rise than fall. Factor this into private retirement savings calculations.

    Strategic Recommendations for 2026

    1. Maximize Private Retirement Vehicles

    With public pension sustainability under pressure, accelerate tax-advantaged private savings:

    • Riester and Rürup pensions (if applicable to your situation)
    • Company pension schemes (Betriebliche Altersvorsorge)
    • Private investment portfolios for flexibility

    2. Review Your Health Insurance Strategy

    With the compulsory insurance limit rising to €77,400, fewer professionals will qualify to exit public health insurance. If you are already privately insured, your advantage grows. If you are approaching this threshold, evaluate whether private insurance makes sense before crossing it.

    3. Compensation Negotiations

    When negotiating salary increases:

    • Focus on gross numbers above contribution ceilings: Income beyond €101,400 avoids pension contributions
    • Non-cash benefits: Company cars, pension contributions, training budgets, these may deliver better net value than straight salary
    • Stock options/equity: Consider structures that defer income to future years with potentially different tax treatment

    4. Tax Optimization and Family Benefits

    The €252 increase in your basic allowance  will not shield you from the contribution squeeze, but other strategies can help:

    • Kindergeld: The €4/month increase (€48/year per child) is negligible. For high earners phased out of Kindergeld, focus instead on maximizing Kinderfreibetrag (child tax allowance) benefits through your annual tax return
    • Maximize work-related expense deductions (Werbungskosten)
    • Investment income strategies utilizing capital gains exemptions

    Final Perspective: The Long-Term Trend

    The 2026 adjustments are not anomalies, they represent an accelerating pattern. Over the past decade, social contribution ceilings have consistently grown faster than tax relief measures. For high earners, this creates a structural headwind:

    • Your income growth is being captured by the social system at an increasing rate
    • Tax relief mechanisms are not keeping pace
    • The pension system you are funding faces demographic and fiscal pressures that make future increases likely

    Proactive wealth planning becomes more critical each year. The gap between what you earn and what you keep will continue to widen unless you actively deploy private savings, tax optimization, and compensation structuring strategies.

    The professionals who thrive in this environment  will not be those who simply accept higher gross salaries, they will be those who architect their total compensation and savings strategies to navigate an increasingly complex fiscal landscape.

    Navigating Your 2026 Financial Strategy

    The fiscal landscape of 2026 introduces several complexities that require more than just a reactive approach. As legislative adjustments to social security and tax frameworks take effect, the necessity for a cohesive, forward-looking strategy becomes paramount for high-earning professionals.

    I provide the expertise to help you develop a comprehensive strategy that accounts for these shifts, ensuring your financial planning remains robust and aligned with your long-term objectives.

    For a deeper analysis of how these changes impact your long-term planning, I invite you to schedule a confidential consultation directly on my website to discuss your specific requirements.

  • The Retirement Gap in Germany: How It Hits High-Income Professionals

    The Retirement Gap in Germany: How It Hits High-Income Professionals

    The Income Cliff: Why High Earners in Germany Face the Steepest Retirement Drop

    If you’re earning a six-figure salary in Germany, you’re likely operating under a dangerous assumption: that the statutory pension system (Gesetzliche Rentenversicherung) scales proportionally with your income.

    It doesn’t.

    The German pension system is structurally designed to cap benefits, creating what we call the Replacement Rate Paradox. While an average earner might retain 48% of their net income in retirement, a high earner could see that figure plummet to 15% or less, not due to poor planning, but by design.

    The entire problem stems from the Beitragsbemessungsgrenze (BBG): the Contribution Assessment Ceiling. In 2025, this ceiling sits at approximately €96,600 annually.

    Here’s what this means in practice:

    • Earning €80,000? You contribute on the full €80,000.
    • Earning €150,000? You still only contribute on ~€96,600.

    Every euro earned above this threshold generates zero additional statutory pension entitlement. Your contributions max out at a level designed for upper-middle-class earners, not executive compensation.

    This isn’t a loophole to exploit, it’s a ceiling that creates a structural retirement deficit for anyone substantially above it.

    The Lifestyle Gap: Running the Numbers

    Let’s make this concrete with a real-world scenario.

    Your current situation:

    • Monthly household expenses: €6,500 (housing, international travel, private education, discretionary spending)
    • Annual gross income: €150,000
    • Years until retirement: 20

    Your projected statutory pension: Even with a perfect 45-year German contribution history, the maximum statutory pension based on the BBG cap is approximately €3,500 gross monthly. After mandatory health insurance contributions and progressive taxation (which increasingly applies to pensioners), your net figure drops to roughly €2,500 per month.

    The gap: €6,500 (lifestyle requirement) – €2,500 (pension) = €4,000 monthly shortfall

    To fund a €4,000 monthly gap for 25 years of retirement, accounting for 3% inflation and conservative 4% real returns, you need approximately €1 million in liquid net assets at retirement age.

    This isn’t discretionary savings, this is a structural liability that requires dedicated capital allocation.

    The challenge compounds for international executives and professionals. The German pension calculation rewards contribution continuity. If your career includes periods in the UK, US, Singapore, or other markets before relocating to Germany, your German contribution record is shorter.

    While EU social security treaties help aggregate contribution periods for eligibility, they don’t increase the value of your German pension points. Your entitlement will likely fall well below the theoretical maximum, widening the retirement gap even further.

    For many of our international clients, the practical statutory pension figure is closer to €1,500–€1,800 net monthly, making the gap even more acute, with low or negative correlations, demonstrating the quantifiable benefit of true diversification.

    Most generic financial guidance centers on simple accumulation: “Save 15% of your income in a diversified ETF portfolio.”

    For high earners in Germany, this approach is both insufficient and tax-inefficient. Here’s why:

    1. You’re saving with net income, not gross In the 42% or 45% tax bracket, every euro you invest has already been taxed. The immediate value destruction is substantial.

    2. The gap requires precision, not accumulation You’re not building wealth from zero, you’re solving a specific liability: bridging a quantified monthly shortfall for a defined period. This is an Asset-Liability Matching problem, not a growth optimization problem.

    3. Time horizon allows for structural advantages With 15+ years to retirement, holding excessive daily liquidity in standard equities carries a significant opportunity cost. You can capture premiums that aren’t available to shorter-term investors.

    Closing a retirement gap of this magnitude requires three structural pillars:

    1. Tax-Leveraged Accumulation

    Deploy capital before taxation wherever possible. In a 42%–45% marginal bracket, the immediate return from tax deferral often exceeds what you’d earn from market alpha. Certain German-compliant structures allow you to invest gross income, creating compounding advantages that dwarf standard after-tax investing.

    2. Capturing the Illiquidity Premium

    Your capital has a 15–25 year lock-up horizon, most high earners hold too much unnecessary liquidity. Allocating a strategic portion to private markets (Private Equity, Infrastructure, Real Estate) allows you to capture the illiquidity premium: the additional 2–4% annual return compensated for longer commitment periods. Over two decades, this difference is transformational.

    3. Strategic Geographic Diversification

    Your retirement income shouldn’t depend entirely on a single jurisdiction’s tax regime or currency. High earners often face the risk of “tax regime shift”: changes in German tax policy that could erode purchasing power decades from now. Building income streams across multiple jurisdictions (whether through international real estate, or multi-currency portfolios) creates both tax optionality and political risk mitigation. When you retire, you’ll have the flexibility to optimize withdrawal strategies based on the most favorable tax treatment available at that time, rather than being locked into a single system.

    High income does not equal high retirement income in Germany. The statutory system wasn’t designed for your compensation level, and standard advice wasn’t designed for your tax situation.

    The Income Cliff is mathematically inevitable, but it’s also solvable with precision planning and the right structural approach.

    We conduct comprehensive Pension Gap Analysis for high earners: a detailed calculation of your projected statutory entitlement versus your actual liquidity requirements, along with a tax-optimized roadmap to bridge the difference.

    If you’d like to see your specific numbers and explore a solution designed for your situation, reach out for a confidential consultation.


    Important Disclaimer: This article provides general information and does not constitute personalized financial advice. Individual circumstances vary significantly, and any financial strategy should be developed in consultation with a qualified advisor familiar with your complete situation.

  • Why Your Portfolio Requires More Than Technology Stocks

    Why Your Portfolio Requires More Than Technology Stocks

    Why Your Portfolio Requires More Than Technology Stocks

    During the 2022 market decline, two investors with identical portfolios targeting 8% annual returns experienced dramatically different outcomes. One saw their portfolio drop 23%, while the other lost just 8%. The difference wasn’t luck, market timing, or stock-picking skill—it was mathematical diversification.

    Consider your investment portfolio as a complex machine that must perform under varied conditions. Many self-directed investors, in pursuit of high returns, concentrate their capital heavily in a single engine: equities, specifically those within the S&P 500, the MSCI World, and technology-focused indices like the NASDAQ.

    While these assets are foundational, reliance solely upon them represents an investment strategy that is incomplete. If all of your holdings operate under the same market dynamics, you have not mitigated your risk effectively.

    Today, we will review the mathematical proof that true diversification across distinct asset classes and geographical regions is not simply conventional wisdom; it is a powerful mechanism for achieving superior risk-adjusted returns.

    The Illusion of Diversification

    An investor may believe he or she is diversified by holding numerous individual stocks or several popular index funds. However, the fundamental concept one must grasp is:

    Effective diversification is achieved by combining assets that possess different behavioral patterns under various economic conditions, not merely by increasing the quantity of holdings.

    When the price of Asset A consistently rises or falls in direct tandem with the price of Asset B, those assets exhibit high correlation. Since most major global equity markets are highly correlated, especially with the United States market, owning multiple stock funds offers little protection during a systematic market decline.

    The Key Concept: Portfolio Variance and Correlation

    In finance, risk is measured by how widely an investment’s price typically fluctuates. Correlation measures how two assets move in relation to each other, expressed on a scale from -1.0 to +1.0.

    When assets are combined into a portfolio, the overall risk is not the simple average of the individual risks. It is significantly influenced by the degree to which their price movements relate to one another—the correlation. Here is a brief explanation of what this means in practice:

    • High Correlation (Near +1.0): If you combine two highly correlated assets, the resulting portfolio risk is nearly identical to the average of the individual risks. There is no risk reduction benefit.
    • Low or Negative Correlation (Near 0 or -1.0): When assets move independently (low correlation) or, ideally, in opposite directions (negative correlation), they serve as a financial hedge. When one asset experiences a downturn, the other may remain stable or even appreciate, thereby smoothing the overall portfolio performance.

    Let us compare two hypothetical portfolios, both constructed with the goal of achieving the same 8% annual expected return, but employing different diversification strategies.

    Portfolio A: The Concentration Strategy

    This portfolio mirrors the high-equity concentration typical of many retail investors, focusing heavily on growth and technology-related sectors.

    • Composition: Heavily weighted in S&P 500, MSCI World, and NASDAQ-focused technology stocks such as Microsoft, Apple, Meta.
    • Characteristic: The average correlation between these assets is extremely high (approximately 0.92).

    Portfolio B: The Multi-Asset Strategy

    This portfolio implements true diversification by combining multiple asset classes designed to perform optimally during different market cycles.

    • Composition: Global Equities, Government Bonds, Real Estate, and Commodities (such as Gold and Oil).
    • Advantage: Government bonds often exhibit a negative correlation with equities during periods of recession. Commodities provide a hedge against unexpected inflation.

    The Quantifiable Outcome

    Our goal is to understand what the current risk of our portfolio is, given that we aim to achieve an expected return of 8%. After all computations, the outcomes are the following:

    PortfolioExpected ReturnCalculated Risk
    A (Concentrated)8.0%22.8%
    B (Diversified)8.0%8.3%

    The Conclusion: Portfolio B achieved the identical expected return with 63% lower risk.

    This massive reduction in volatility is the direct result of combining assets with low or negative correlations, demonstrating the quantifiable benefit of true diversification.

    Risk Mitigation in Practice

    The difference between 22.8% risk and 8.3% risk translates directly to the magnitude of losses experienced during market turmoil. The following scenarios are illustrative examples based on historical asset class behavior during these periods:

    Market ScenarioPortfolio A (Concentrated)Portfolio B (Diversified)
    2008 Financial Crisis-42% Loss-18% Loss
    2022 Inflationary Shock-23% Loss-8% Loss

    In scenarios of systemic risk or unexpected inflation, the diversified portfolio (B) provided a significantly smoother path, reducing the severity of drawdowns and preserving capital when it matters most.

    These numbers represent more than statistical abstractions. They represent the difference between maintaining your retirement timeline and being forced to delay it by years. They represent the difference between weathering market storms with confidence and lying awake at night during periods of volatility.

    While the mathematics of diversification are straightforward, practical execution is considerably more complex than many investors realize.

    The Hidden Complexities

    Correlation Analysis: Asset correlations are not static. They shift across different market regimes, economic cycles, and geopolitical conditions. What provides diversification benefit today may not tomorrow.

    Strategic Rebalancing: Effective rebalancing (meaning adjusting the proportion of each type of investment in your portfolio) requires more than an annual calendar reminder. It demands an understanding of when to rebalance (triggered by market movements or time periods), tax implications of selling positions, and the discipline to execute counter-intuitive trades during market extremes.

    Asset Selection Within Classes: Simply purchasing “a bond fund” or “a commodity ETF” is insufficient. Which geographical exposure? Which duration for bonds? Which commodities and in what proportion? Each decision compounds the complexity.

    Behavioral Discipline: The greatest threat to portfolio performance is often the investor himself. During periods of exceptional equity performance, the temptation to abandon a diversified approach and chase returns is overwhelming. Conversely, during market declines, panic selling undermines the entire strategy.

    The Cost of Errors

    A seemingly minor miscalculation in portfolio construction—selecting assets with higher correlations than anticipated, failing to rebalance at critical moments, or allowing emotional responses to override mathematical discipline—can erode decades of accumulated wealth.

    The difference between a properly constructed multi-asset portfolio and a haphazard approximation may not be apparent during bull markets, but it becomes painfully evident during corrections.

    The evidence is unambiguous. True diversification, defined mathematically by low correlations between asset classes, dramatically reduces portfolio volatility without sacrificing expected long-term returns. However, understanding the theory and successfully implementing it are distinctly different challenges.

    If you recognize that your current portfolio may be more concentrated than you realized, or if the complexities of constructing and maintaining a truly diversified strategy seem daunting, you are not alone. This is precisely why professional portfolio management exists—not to deliver market-beating returns through speculation, but to apply rigorous mathematical principles and disciplined execution that most investors struggle to maintain independently.

    The question is not whether diversification works. The mathematics prove it does. The question is whether your portfolio is genuinely diversified, properly balanced, and positioned to protect your financial future.

    Take the Next Step

    If you would like to discuss how these principles apply specifically to your investment situation, we invite you to schedule a complimentary portfolio analysis. A conversation costs nothing, but the insights gained from a professional portfolio review could prove invaluable to your long-term financial security.


    Important Disclaimer: This article is provided for educational purposes only and does not constitute personalized investment advice.

  • Early Repayment of a Mortgage Loan: Advantages, Disadvantages, and Tips

    Early Repayment of a Mortgage Loan: Advantages, Disadvantages, and Tips

    Early Repayment of a Mortgage Loan : Good or Bad Idea? 

    Introduction 

    Faced with a cash surplus, many homeowners ask themselves this crucial question: should I prepay my mortgage or invest the money elsewhere? This seemingly simple decision actually hides a complex financial equation that deserves in-depth analysis. 

    While the idea of getting out of debt faster is psychologically appealing, it isn’t always the most profitable strategy. Let’s break down the mechanisms at play to help you make the best decision. 

    How Do Early Repayments Work? 

    Early repayments, known as Sondertilgung in Germany, allow you to reduce the borrowed capital with exceptional payments. These additional payments have two immediate effects: 

    • Reduction of future interest: Less capital means less interest to pay. 
    • Shortening the loan term or decreasing monthly payments. 

    Most loan agreements permit early repayments of 5 to 10% of the initial capital per year, sometimes without penalty. 

    Numerical Analysis: Two Revealing Examples 

    Example 1: Classic Repayment 

    Consider a loan of €300,000 over 25 years at 3.5%

    • Without early repayment: 
    • Monthly payment: €1,501 
    • Total interest: €150,375 
    • Total cost: €450,375 
    • With a €15,000 repayment in the 3rd year: 
    • Interest savings: €16,950 
    • Term reduction: 1 year and 9 months 
    • Revised total cost: €433,422 

    Example 2: The Decisive Impact of Timing 

    Let’s analyze a more complex case: €400,000 over 10 years at 3.2% with a 2% amortization rate. 

    • Initial configuration: 
    • Monthly payment: €1,733 
    • Remaining capital after 10 years: ~€305,000 
    • Scenario A: €20,000 repayment in the 1st year 
    • Interest savings: €7,457 
    • Remaining capital after 10 years: ~€278,400 
    • Difference in remaining capital after 10 years: €26,600 
    • Scenario B: €20,000 repayment in the 8th year 
    • Interest savings: €1,954 
    • Remaining capital after 10 years: ~€283,910 
    • Difference in remaining capital after 10 years: €21,090 

    Key Lesson: Timing Is Crucial 

    This comparison reveals a fundamental truth: an early repayment generates 3.8 times more interest savings if it’s made at the beginning of the loan rather than the end. The reason is simple: at the start, the portion of interest in the monthly payments is at its maximum. 

    Why It’s Not Always a Good Idea 

    1. The Opportunity Cost of Investments 

    If you can invest with a return higher than your loan’s interest rate, it’s better to invest than to repay. 

    Concrete example: With our €15,000 invested at 6% per year for 22 years: 

    • Final value: €54,053 
    • Net gain vs. repayment: €22,103 more 
    1. Loss of Liquidity 

    Money invested in an early repayment becomes completely illiquid. In an emergency, it’s impossible to get it back quickly. 

    1. Lost Tax Advantage 

    For rental property investments, loan interest is tax-deductible. Prepaying loses this advantage: 

    • Annual tax impact: Interest × Marginal tax rate 
    • For an investor taxed at 42%: total deduction loss of €7,120 on €16,950 of interest. 

    Optimal Strategies by Profile 

    • The Prudent 
    • Repay if no risk-free investment exceeds the loan rate. 
    • Keep 6 months of living expenses in reserve. 
    • Prioritize repayments at the beginning of the loan. 
    • The Investor 
    • Systematically compare with investment opportunities. 
    • Diversify your assets rather than betting everything on real estate. 
    • Exploit the leverage effect as long as it’s profitable. 
    • The Pragmatist 
    • Adopt a mixed approach: 50% repayment, 50% investment. 
    • Adjust the allocation based on changes in interest rates. 
    • Re-evaluate the strategy annually. 

    Pitfalls to Avoid 

    1. A Purely Emotional Decision 

    Getting out of debt provides psychological satisfaction, but it can be financially costly. 

    1. Neglecting Inflation 

    A fixed-rate loan becomes cheaper in real terms with inflation. 

    1. Forgetting Taxation 

    The tax implications can completely reverse the equation. 

    1. Lacking Flexibility 

    Money “locked” in a repayment can no longer seize opportunities. 

    Practical Recommendations 

    • Calculate the real return by including taxation and inflation. 
    • Preserve your investment capacity by keeping liquidity. 
    • Diversify your assets instead of concentrating everything on real estate. 
    • Renegotiate rather than repay if rates have fallen. 
    • Prioritize early repayments at the beginning of the loan term. 
    • Consult an independent advisor for a personalized analysis. 

    Conclusion: A Tailor-Made Decision 

    Early repayment of a mortgage is neither systematically a good nor a bad idea. It all depends on your personal situation, the economic environment, and your wealth objectives. 

    Early repayments are a good idea when: 

    • You have no more profitable investment alternatives. 
    • You are in the early stages of the loan. 
    • You have built up your emergency savings. 

    They are not recommended when: 

    • Investments offer a better return. 
    • You benefit from tax advantages on interest. 
    • You lack liquidity. 

    The key lies in a rigorous financial analysis, because ultimately, the goal isn’t to repay as quickly as possible, but to optimize your overall assets. 

    Need Personalized Advice? 

    Every financial situation is unique, and the calculations presented in this article cannot replace a personalized analysis of your case. If you want to determine the optimal strategy for your specific situation—taking into account your tax profile, your wealth objectives, and the current economic environment—do not hesitate to contact me. 

    A tailor-made study will allow you to make an informed decision and truly optimize your repayment or investment strategy. 

  • How does money creation work?

    How does money creation work?

    Understanding what’s really behind our everyday money.

    I. A Bread for… Code?

    When we pay for a bread at the bakery, we hand over a banknote, a coin, or use our bank card. But in reality, we’re not giving a “good” with intrinsic value; we’re exchanging a piece of paper, or a line of code, for a tangible item.

    This simple act hides a complex economic and social construct: today’s money is no longer backed by gold or a physical asset. Its value is based on trust and the mechanisms of monetary policy.

    II. From Barter to Book Money

    In ancient societies, exchanges were done through barter: a loaf of bread for a fish. But this system quickly showed its limits: not all goods are easily divisible, storable, or exchangeable. This is how money first appeared, initially in the form of precious goods (salt, gold, shells), then as coins minted by the state, and finally, as banknotes and scriptural money (electronic money).

    The shift to fiat money was a major break. Unlike gold coins, this money derives its value from the trust placed in the issuing authority and its general acceptance. This transition accelerated with the abandonment of the gold standard in 1971, marking the definitive entry into the era of modern money.

    Today, the vast majority of money in circulation is neither coins nor banknotes: it’s book money, created by commercial banks when they grant loans. In the Eurozone, this electronic money represents about 85% of all money in circulation.

    III. How Do Banks Actually Create Money?

    1. The Creation Process by Commercial Banks

    Contrary to popular belief, the Central Bank doesn’t create all the money. It’s primarily commercial banks that do it every day:

    A concrete example: Marie wants to buy an apartment for 300,000 euros. She goes to her bank for a mortgage. The bank approves her request. At that precise moment, the bank:

    • Deposits +300,000 euros into Marie’s current account.
    • Records +300,000 euros in its receivables (what Marie owes them).

    These 300,000 euros did not exist before. The loan creates the deposit, not the other way around. This money creation happens instantly, through a simple accounting entry.

    2. The Role of the Central Bank

    The Central Bank’s role is different:

    • It refinances banks: When a bank is short on liquidity, it can borrow from the ECB.
    • It buys bonds on the markets (especially during crises).
    • It issues the banknotes we use daily.

    The ECB, therefore, does not directly create all the money, but it controls the conditions under which banks can create it.

    IV. The Limits to Money Creation

    Money creation is not unlimited. Several constraints govern it:

    1. Regulatory Constraints

    Required Reserves: Banks must deposit 1% of their customer deposits with the ECB. If a bank has 100 million in deposits, it must lock up 1 million with the ECB.

    Solvency Ratios: Since the 2008 crisis, banks must prove they have enough capital to absorb potential losses. They must maintain a minimum ratio of 8% between their equity and the loans they have granted.

    2. Practical Constraints

    Leaking between banks: When Marie uses her €300,000 loan to buy her apartment, the seller might be a client of another bank. Her bank will then have to transfer these 300,000 euros to the seller’s bank. It must, therefore, have this liquidity.

    Cost of financing: Banks must finance their activities. If they grant too many loans, they’ll have to borrow on the markets or from the ECB, which comes at a cost.

    Risk assessment: Banks only grant loans if they believe the borrower can repay. This assessment naturally limits money creation.

    3. Inflation as a Limit

    If too much money is created relative to the goods available, prices rise (inflation). Historical examples show the dangers: 1920s Germany, where a wheelbarrow of banknotes was needed to buy bread, or more recently, Venezuela, where inflation exceeded 1,000,000%.

    V. Monetary Policy Tools in Practice

    1. Interest Rates

    The ECB sets its key interest rates, currently around 2%. These rates influence the cost of loans:

    • If the ECB lowers its rates, banks can borrow more cheaply and pass on this reduction to their customers.
    • If it raises them, the opposite effect occurs.

    2. Injecting Liquidity

    During crises (2008, 2020), the ECB massively buys government and corporate bonds to inject liquidity into the economy. These programs, called “quantitative easing,” amount to thousands of billions of euros.

    3. Communication

    The ECB regularly communicates its future intentions. These “signals” guide the decisions of banks and investors even before measures are taken.

    VI. How Is Money Measured?

    Economists distinguish several “layers” of money:

    • M1: Immediately usable money (banknotes, coins, current accounts).
    • M2: M1 + easily mobilizable savings (time deposits of less than 2 years).
    • M3: M2 + slightly less liquid investments (money market funds, short-term bonds).

    The ECB mainly monitors M3, which represents the total money circulating in the European economy.

    VII. Current Transformations

    1. The Digital Revolution

    Bitcoin and cryptocurrencies: These digital currencies operate without central banks. Bitcoin, for example, is created through a computer process called “mining.” About 10,000 new bitcoins are created daily according to pre-programmed rules.

    Official digital currencies: China is already testing its “digital yuan” with millions of users. Europe is studying a “digital euro” that would allow direct payments with central bank money, bypassing commercial banks.

    Stablecoins: Digital currencies like Tether or USDC claim to be backed by “real” dollars. They now represent over $150 billion in capitalization.

    2. Exceptional Policies Since 2008

    Since the 2008 financial crisis, central banks have created unprecedented amounts of money:

    • The US Fed: injected more than $8 trillion.
    • The ECB: purchased over €5 trillion through its programs.
    • The Bank of Japan: bought bonds equivalent to its GDP.

    These amounts represent several times the annual budgets of the countries concerned.

    3. Negative Rates

    Between 2014 and 2022, the ECB set its rates in negative territory. Banks had to pay to deposit their money with the ECB, a historically unprecedented situation. The goal was to encourage them to lend rather than hoard.

    VIII. Conclusion

    Money creation, long considered a technical mechanism reserved for specialists, is becoming a central issue in contemporary economic and political debates. Understanding it helps to decode major economic developments and anticipate their impacts on our daily lives.

    The ongoing transformations—digitalization, exceptional monetary policies, new actors—are redefining the contours of a centuries-old system. These changes directly affect our payment methods, our savings, and our relationship with money in general.

    Mastering these issues is essential for any citizen who wants to understand current economic debates and the political choices shaping the future of our societies.

    Understanding money creation is a first step. But knowing how to effectively use your money in this constantly changing context requires a personalized and professional approach.

    Schedule an appointment for a personalized consultation and discover how to:

    • Optimize your savings in an environment of fluctuating rates.
    • Take advantage of financial innovations while controlling risks.
    • Build a coherent wealth strategy aligned with ongoing developments.

    Financial expertise is essential to navigate this transforming monetary landscape. Contact us to analyze your situation and define a financial strategy tailored to your goals and the current economic context.