Invest All at Once or Gradually: What the Data Actually Says
The intuitive answer is usually wrong. Here’s why and when it’s right.
You’ve just received a significant sum, an inheritance, a bonus, the proceeds from a property sale. And the question immediately follows: do I invest everything at once, or do I spread it out over several months to reduce risk?
Most people’s instinct is to spread it out. It feels safer, more measured and it avoids the unsettling thought of having “put everything in” just before a market drop.
That instinct is human. It’s understandable. And in most situations, it costs you money.
Here’s why and in which specific cases spreading out remains the right call.
I. The Two Strategies, Clearly Defined
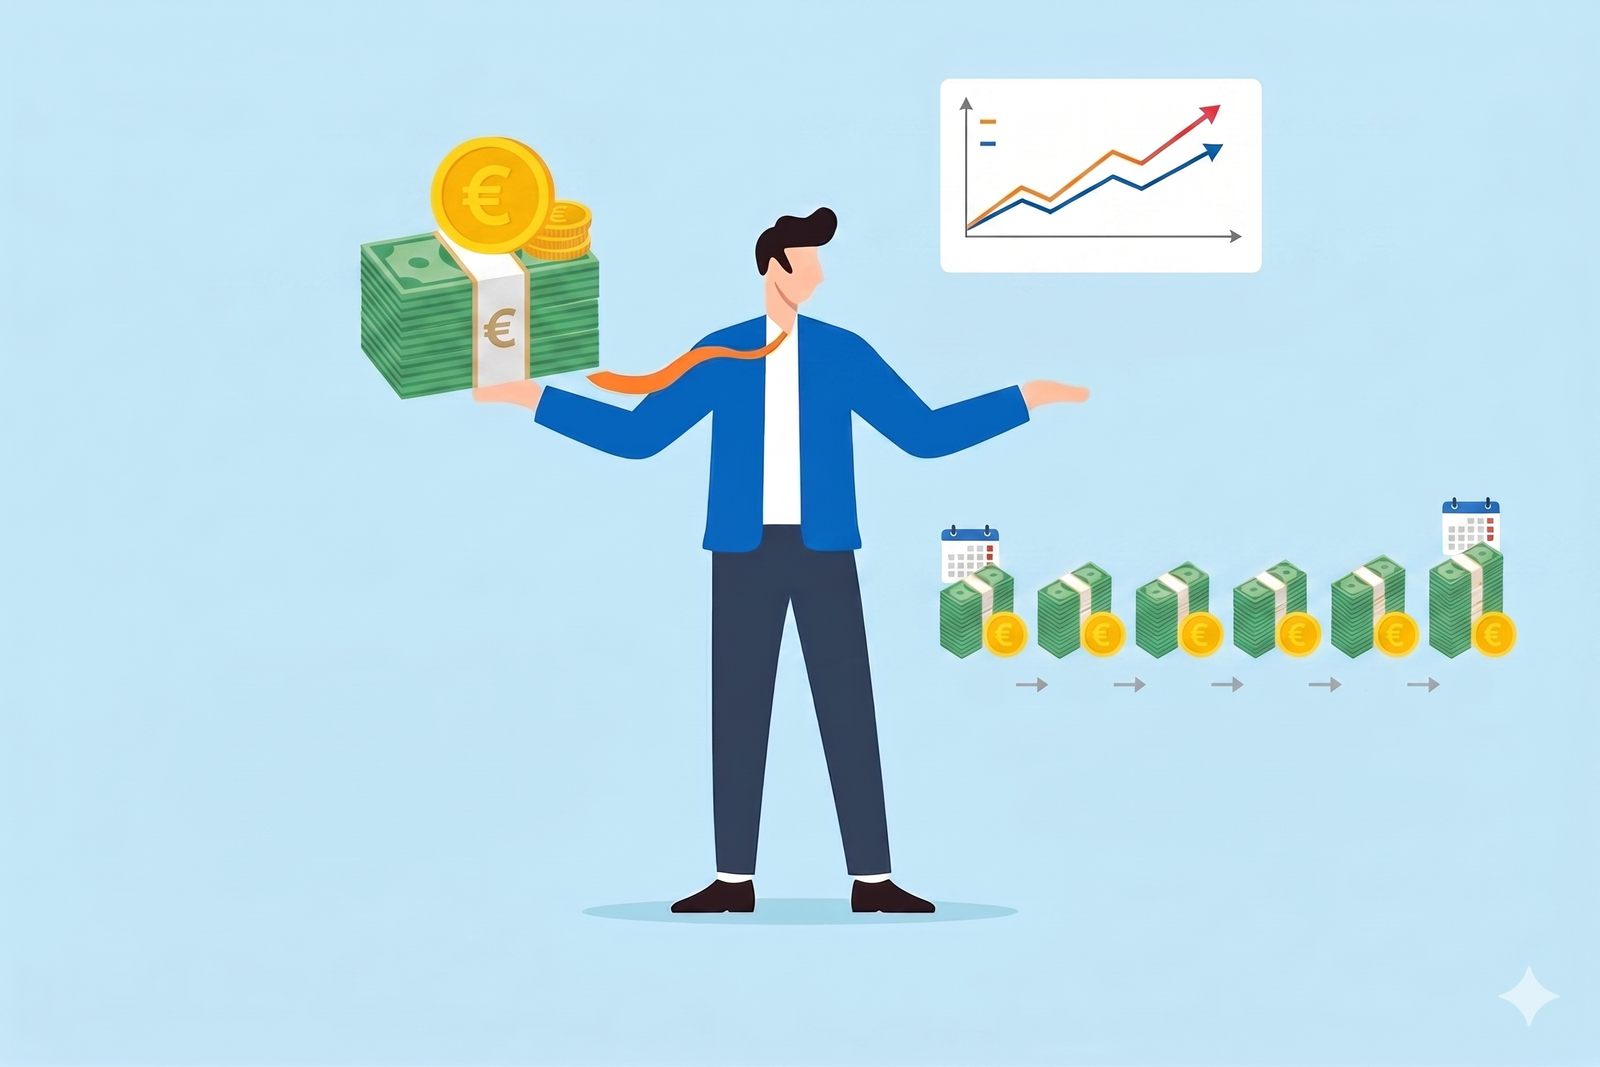
Lump Sum investing: you invest your entire available capital on day one. If you have €60,000, it goes in on 1 January, and the market does what it does with the full amount from that point forward.
DCA (Dollar-Cost Averaging): you split your capital into equal instalments invested at regular intervals, for example, €10,000 on the 1st of each month for six months. The idea is that you don’t buy everything at the same price: if the market falls, the subsequent instalments are bought more cheaply.
Neither approach is inherently right or wrong. Their relevance depends on context, asset class, and, we’ll come back to this, your actual psychological profile as an investor.
II. What the Research Shows
The reference study is Vanguard’s 2012 paper “Dollar-Cost Averaging Just Means Taking Risk Later”, which analysed thousands of 12-month historical periods across US, UK, and Australian markets going back to the 1920s.
The main finding: investing in a lump sum outperforms dollar-cost averaging in approximately 66% of cases: two times out of three. The average performance difference is around 2.3 percentage points over 12 months.
On a €100,000 capital base, 2.3% is €2,300 in a single year. Over 20 years, with the compounding effect (gains generating further gains), that gap becomes very difficult to close.
This pattern holds across all time periods and all markets studied. It is not a statistical accident driven by one exceptional decade, it is a structural tendency.
III. The Mechanics: Why Waiting Costs Money
Over the past forty years, global equity markets have risen in approximately 63% of calendar months. In other words, if you pick a random month from recent history, there is a 6-in-10 chance the market went up that month.
What this means in practice: when you decide to spread your investment over 6 months rather than investing immediately, you are statistically more likely to be buying at progressively higher prices than to be finding cheaper entry points. Spreading out is an implicit bet that the market will fall, a bet that has historically been wrong 63% of the time.
Money on the sidelines is not neutral
Capital waiting to be invested doesn’t work. Sitting in a current account or a money market fund, it earns little or nothing, while the market, most of the time, moves forward without it.
On €60,000 spread over 6 months, half the capital waits an average of 3 months before being invested. If the market grows at 8% per year over that period, those 3 months of inactivity represent approximately €600 in missed performance, before even comparing the different purchase prices of each instalment.
IV. The Numbers in Practice: A Simulation on Real Data
Claire, 41, receives an inheritance of €60,000 in December and wants to invest it in an MSCI World ETF, an index fund that tracks the performance of approximately 1,500 large companies worldwide.
She compares two scenarios over 6 months.
The parameters:
| Parameter | Value |
| Available capital | €60,000 |
| Instrument | MSCI World ETF |
| Purchase price in December | 110.78 |
| Price on 1 June | 123.83 |
| DCA strategy | €10,000 per month, over 6 months |
| Purchase price in May (DCA) | 116.39 (5% more than in December) |
Results:
| Strategy | Initial outlay | Value in June | Gain | Return |
| Invest everything in December | €60,000 | €67,065 | +€7,065 | +11.78% |
| Spread over 6 months (DCA) | €60,000 | €66,244 | +€6,244 | +10.41% |
| Difference | — | — | +€821 | +1.37 pts |
Illustrative simulation on real data. Past performance is not indicative of future results.
Over this rising period, investing in a lump sum generates €821 more. The reason is mechanical: the €60,000 benefits from market growth from day one. With DCA, the April, May, and June instalments are bought at progressively higher prices, the market didn’t wait.
What if the market had fallen?
Over a falling period, the gap reverses. DCA would have allowed the purchase of units at progressively lower prices, reducing the overall loss. But falling 6-month periods are statistically less frequent than rising ones, which is what the two-thirds figure in the Vanguard study reflects.
V. When Spreading Out Is the Right Decision: Asset-by-Asset Analysis
| Asset type | Recommended approach | Why |
| Equities and index funds (ETFs) | Lump sum | Markets rise 2 times out of 3; every month of waiting has a cost |
| Gold and commodities | Spread gradually (DCA) | High volatility, no holding income, price smoothing is relevant |
| Real estate, REITs, SCPIs | Lump sum | Generates rental income from day one, every month of delay is a lost rent |
| Private equity funds (ELTIFs) | Determined by the fund | These funds call capital progressively, you don’t decide the timing |
Gold and commodities: when spreading makes sense
Gold pays no dividend and generates no income while you hold it. Its value depends entirely on price movements in the market. Facing an asset this unpredictable, with no holding income, entering “all at once” at the wrong moment is offset by nothing. Here, gradual entry genuinely reduces that risk.
Real estate and SCPIs: the rental income argument
A SCPI unit, a collective property investment vehicle that distributes rental income to investors, generates income from the first day of ownership. At a net yield of 5% per year, €60,000 not invested for 6 months represents approximately €1,500 in rent you are deliberately forgoing.
Private equity funds: when the structure decides
ELTIFs and other private equity funds call your capital in tranches, in line with their own investment pace. You do not choose when to deploy, the fund manager decides. The DCA vs lump sum question generally does not apply here.
VI. Investor Psychology: What Spreading Reveals and What It Costs
Why our brains prefer spreading out
Behavioural economists, most notably Daniel Kahneman, Nobel Prize in Economics, have shown that the pain felt from a loss is roughly 2.5 times more intense than the pleasure generated by an equivalent gain. In plain terms: losing €1,000 hurts psychologically far more than gaining €1,000 feels good.
The result: if you invest €60,000 in one go and the market drops 10% the next day, seeing €6,000 “evaporate” in 24 hours triggers a strong emotional reaction, even if over 10 or 20 years it changes nothing about the final outcome. Spreading out protects against that immediate pain.
The real cost of your psychological comfort
Spreading out does not reduce your portfolio’s long-term risk. It trades slightly lower performance for better short-term psychological comfort. That is a conscious trade-off, not a risk-reduction strategy.
A strategy held for 20 years is worth infinitely more than a mathematically optimal one abandoned in a moment of panic.
The honest question to ask is therefore not “which strategy is better?” but: what is the real cost of my psychological comfort, and am I accepting it consciously?
VII. How to Decide in Your Situation
1. Do you actually have a lump sum available? If you are investing your monthly savings as they come in, DCA is not a choice, it is your reality. The question only arises when you have a single sum available all at once.
2. What type of asset are you targeting? Refer to the table in Section V. For equities and index funds, the data leans clearly towards lump sum. For gold and no-income assets, gradual entry is more defensible.
3. What is your real risk tolerance? Practical test: if your investments lose 20% of their value in the month following your purchase, how likely are you to sell? If that probability is high, spreading out is not an acceptable underperformance, it is a necessity for staying invested.
4. Is a hybrid approach right for you? A middle-ground option exists: invest 60 to 70% immediately, and spread the remainder over 2 to 3 months. This structure captures most of the statistical advantage of lump sum investing while limiting full exposure to poor timing on the entire capital. For many investors, this is a pragmatic and psychologically sustainable compromise.
Conclusion
The DCA vs lump sum question has no universal answer, but it has structured ones. In equity markets, the data is clear: investing in one go outperforms two times out of three, and the difference compounds over time. In other asset classes, such as gold or commodities, the logic changes.
What never changes is the underlying principle: a capital deployment decision deserves to be made with a clear understanding of its real implications, financial, psychological, and tailored to the specific nature of what you are buying.
You’ve just received a sum to invest and you’re unsure of the best approach?
The right strategy depends on your specific situation: your goals, your time horizon, your existing assets, your tax position, and your real psychological profile around risk. These are exactly the questions we work through together in an initial conversation.
→ Book a 30-minute discovery call
This article is published for informational purposes only and does not constitute personalised investment advice. Any investment strategy requires prior examination of your individual situation in a dedicated consultation. Historical performance figures cited are not indicative of future results. Investing involves risk, including the risk of loss of capital.