Category: Retirement

  • Riester contract: what to do in 2027, now that the Altersvorsorgedepot is here

    Riester contract: what to do in 2027, now that the Altersvorsorgedepot is here

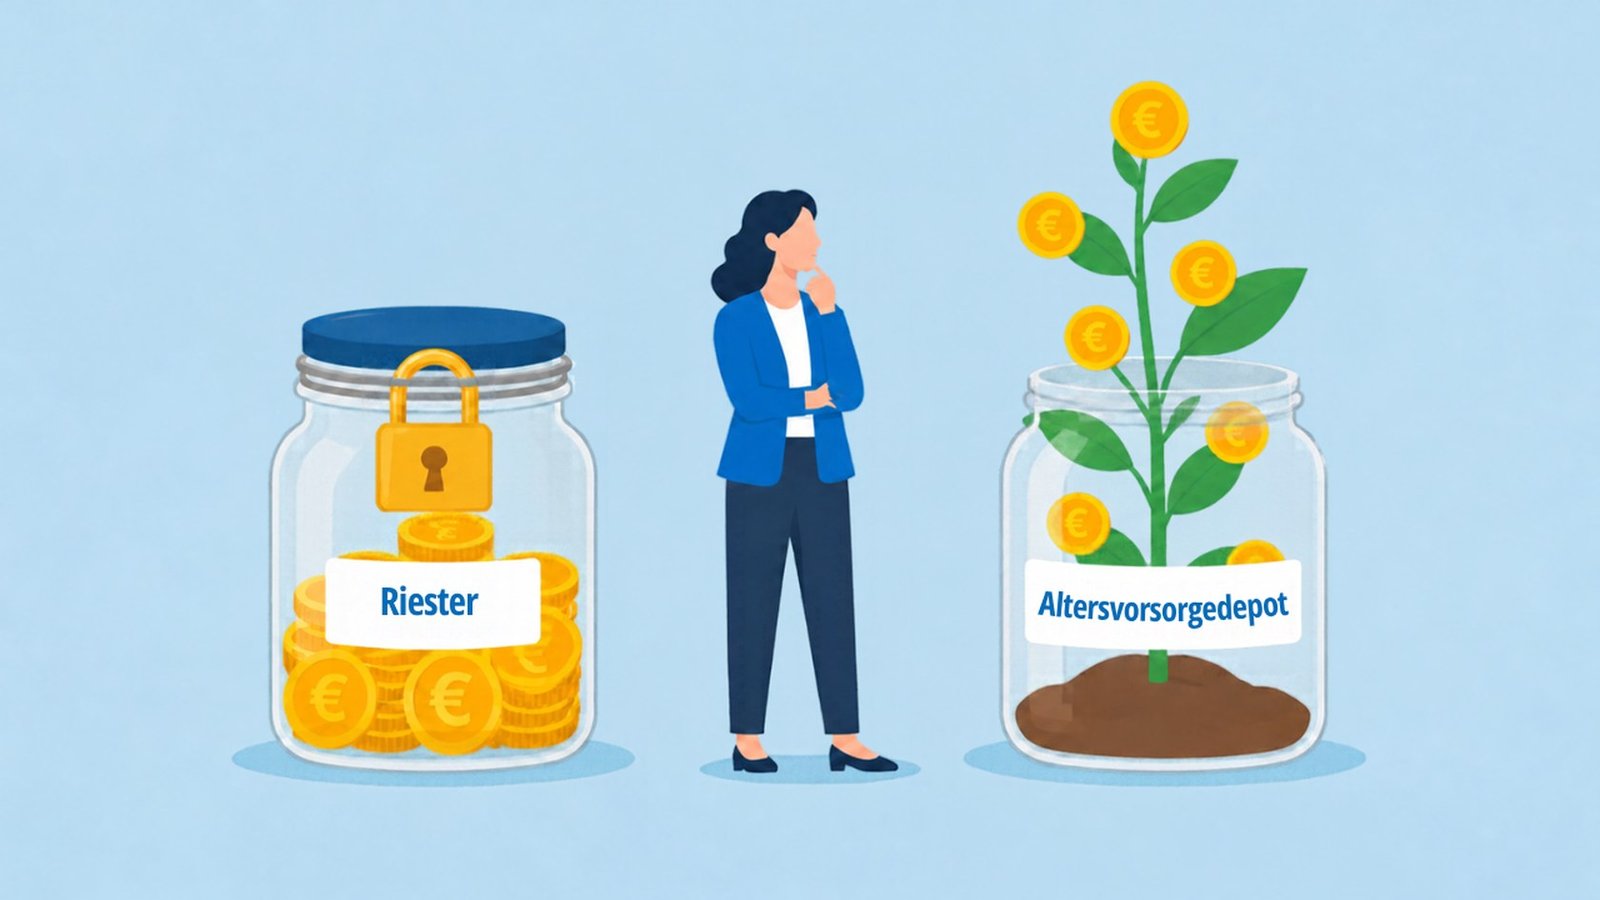
    You signed a Riester contract a few years after moving to Germany. Since then, a payment has gone out every month, and you are not really sure what it earns you. In January 2027, banks, online brokers and insurers will start offering you the new Altersvorsorgedepot, often in a few clicks.

    Nothing forces you to act. But some steps, once taken, cannot be undone. This article sets out your options for your Riester contract and what to check before you choose.

    To understand the new product itself (subsidies, fees, payout), start with my Altersvorsorgedepot 2027 guide.

    Your Riester contract stays valid

    A Riester contract signed before 1 January 2027 keeps its existing rights (Bestandsschutz). You can carry on exactly as today, under the old subsidy rules (source: Federal Ministry of Finance, BMF). There is no automatic cancellation and no automatic conversion (source: Federal Government).

    You also keep the right to pause your contract (ruhen lassen): the law requires it for old and new contracts alike (source: BMF).

    This protection gives you time to compare: nothing forces you to decide on 1 January. What matters is not to sign anything before you have compared.

    The four options for your contract

    The reform leaves you four possibilities (source: BMF).

    1. Carry on unchanged

    Your contract and your payments stay the same, under the old subsidy rules. The capital stays where it is.

    2. Keep the contract, switch to the new subsidy rules

    A simple declaration to your provider is enough; the provider does not have to agree. The terms of the contract stay the same; only the way subsidies are calculated changes.

    3. Transfer to a new contract

    Your capital moves to an Altersvorsorgedepot or a guaranteed product, under the new rules. You do not repay the subsidies already received, but switching, sales and distribution costs may apply.

    4. Stop paying in and open a new contract

    The old contract is paused and the capital stays there until retirement. Your new payments go into the new contract, under the new rules. Be aware: you then move to the new subsidy rules, including for the old contract, although its original terms (guarantee, any guaranteed interest rate) remain intact (see below).

    Once you have left the old subsidy rules, there is no way back (source: BMF). That is why the order of your decisions matters.

    The trap: opening an Altersvorsorgedepot alongside your Riester

    Many savers plan to keep their Riester as it is and simply open an Altersvorsorgedepot on top. That is allowed: the law permits up to two new contracts alongside the old one. But as soon as you sign the new contract, you move to the new subsidy rules, and your Riester loses its protected status (source: BMF).

    In practice, your old contract no longer falls under the old subsidy rules, and you cannot go back. Opening an account online takes a few minutes; this consequence is permanent.

    What changes is the way subsidies are calculated, not the contract itself: the guarantee and any guaranteed interest rate stay in place as long as you neither transfer nor cancel. If the old contract is paused, losing the old rules costs it nothing. The trap concerns people who intend to keep paying into the old contract, and above all lower earners: the old rules gave them the full subsidies for a small payment (see example 3 below).

    Transferring the capital (option 3) calls for a different check. When you leave your contract, you also leave its terms: guarantees, any guaranteed interest rate on an older insurance contract, built-in options. Before you tick “transfer my Riester” on a form, know what those terms are worth.

    Cancelling to get the money: the most expensive option

    Cancelling your contract to have the capital paid out is not the same as a transfer. For the tax authorities, it is a harmful use (schädliche Verwendung) of subsidised savings (source: BMF; Income Tax Act, § 93 EStG).

    • The subsidies must be repaid: all of those received while saving, plus the tax savings obtained through the tax deduction (source: BMF; § 93 EStG).
    • The gains are taxed: the amount paid out, minus the subsidies, is taxable for the part that corresponds to the contract’s gains (source: § 22 no. 5 EStG). Your tax adviser (Steuerberater) can put a figure on this for your case.
    • The guarantee disappears: you get the current value, after the costs already deducted. On a contract at a loss, the loss becomes final.

    For a saver with two children who received the full subsidies for ten years, the subsidies alone to be repaid come to €7,750. On top of that come the tax savings obtained, often significant on a high income, and then the tax on the gains.

    If you need flexibility, other routes avoid this repayment: pausing the contract (the subsidies already received are kept), transferring the capital to another certified contract (option 3) or, for a home purchase, using the withdrawal allowed for owner-occupied housing (Wohn-Riester).

    Is your contract at a loss?

    This is the first thing to check. According to the consumer advice centre of Baden-Württemberg (Verbraucherzentrale), Riester contracts often remain in the red for years after signing, mainly because of acquisition costs.

    Why? The law requires the provider to guarantee that, when retirement payments start, at least the contributions paid in will be available (source: AltZertG, § 1). To keep that promise, some providers sold equity fund units at the bottom of the 2008 and 2020 crashes and moved savings into bonds. According to the same Verbraucherzentrale, in its statement to the Bundestag, the 2022 interest rate rise then caused price losses of up to 50%.

    The key point: this guarantee only applies when retirement payments start. If you transfer your capital before then, you leave with its current value. A paper loss becomes a real loss, and the guarantee of the old contract disappears.

    That does not mean you should always stay. A contract stuck in bonds can also take years to recover. But the decision should be made knowing this figure.

    How to check: every year, your provider must tell you in writing the capital built up, the actual costs of the past year, the returns achieved and, for more recent contracts, the capital expected at the start of payments (source: AltZertG, § 7a). Compare the current capital with your payments plus the subsidies received.

    What a switch costs

    A transfer is not a cancellation with a payout: you ask for the capital to move directly from your current contract to the new one. In general, the new provider handles the request with your current provider. Legally, it is a termination for the purpose of transfer, with three months’ notice to the end of a calendar quarter (source: AltZertG, § 1). Never ask for the money to be paid out to you: that would be a cancellation, with the consequences described above.

    Possible costs:

    • Your current provider: if your contract is less than five years old, it may charge at most €150 for the transfer. After five years, the transfer is free (sources: AltZertG, § 1, version in force from 1 January 2027; BMF).
    • The new provider: a one-off administration fee of at most €150. It may not calculate acquisition and distribution costs on the subsidised capital you transfer. Those costs may, however, apply to your future payments, spread over the whole savings period (sources: AltZertG, § 1, 2027 version; BMF).
    • Costs already paid on the old contract: you do not get them back. In a Riester contract, acquisition and distribution costs are spread over at least the first five years (source: AltZertG, § 1). On an older contract, much of them has therefore already been paid: what matters from now on is the costs still to come.

    To find out the costs of your contract, go back to the product information sheet (Produktinformationsblatt) handed to you at signing (for contracts signed since 2017): it sets out the costs and the conditions for switching and cancelling (source: AltZertG, § 7). Your annual statement shows the costs actually charged last year.

    The same rules apply to later switches within the new system (source: BMF).

    Old or new subsidy rules: what to compare

    The two systems do not calculate subsidies the same way. Depending on your income and your family, one can pay noticeably more than the other.

    CriterionOld rules (Riester)New rules (2027)
    Basic subsidy€175 a yearThe state adds 50 cents per euro paid in up to €360 (i.e. €180), then 25 cents per euro from €361 to €1,800 (up to €360 more). Maximum: €540 a year.
    Per child€300 (born from 2008) or €185 (born before)The state adds €1 per euro paid in, up to €300 per child.
    To get it in fullPay in 4% of the previous year’s income (€2,100 maximum), minus the subsidies, and at least €60 a year. Otherwise subsidies are reduced pro rata.At least €120 a year. The subsidy follows what you pay in.
    Tax deduction cap€2,100, subsidies includedUp to €1,800 of your own payments, plus the subsidies
    GuaranteeAt least the contributions paid in100%, 80% or none, depending on the product
    Earliest payoutAge 62 (60 if signed before 2012)Age 65, earlier if you already draw a statutory pension

    Sources: BMF; Finanzamt NRW for the Riester minimum contribution.

    Example 1: a manager earning €80,000 gross, two children born from 2008. The new rules win. Under the old rules, he must pay in €1,325 a year to receive €775 in subsidies. Under the new rules, paying in €360 is enough to receive €780, and if he keeps paying €1,325, he receives about €1,021. At this income level, the tax deduction often matters more than the subsidies, and its cap rises too (see the table).

    Example 2: a married couple, she works part-time for €36,000 gross, three children. A draw. As is common for married couples, she receives the child subsidies. Under the old rules, she must pay in €365 a year to receive €1,075. Under the new rules, the same €365 brings in €1,081. The difference is negligible: the choice will come down to other criteria (guarantee, costs, age, plans).

    Example 3: a married couple, she went back to work half-time for €24,000 gross, two children. The old rules win. Under the old rules, paying in €185 a year brings her €775. Under the new rules, the same €185 brings in only about €463, and she would have to pay in €350 to get back to €775. Here, keeping the old rules is clearly better.

    In both systems, the tax office also checks whether a tax deduction is more favourable to you than the subsidies (source: BMF). If your spouse also has a contract, or opens one through your entitlement, their situation enters the calculation too.

    I can run this calculation with you, on your own figures, in a first conversation.

    Your age and the time left before retirement

    Age matters in two ways.

    The age at which the money becomes available. A Riester contract can start paying out at 62, or at 60 if it was signed before 2012 (source: Deutsche Rentenversicherung). In the new system, payments start at 65 at the earliest, unless you already draw a statutory pension (source: BMF). If you are thinking of stopping work early, this point matters before any transfer.

    The number of saving years left. The further away retirement is, the more time subsidies and returns have to build up, and the more time an unguaranteed investment has to ride out downturns. A few years before retirement, the guarantee of your old contract and its current value weigh more. The new standard product reflects this: it automatically shifts savings into the more cautious fund in the years before retirement (source: BMF).

    If your contract is at a loss. Close to retirement, keeping it is often the more prudent choice: the guarantee will return at least your contributions when payments start, whereas a transfer locks in the loss. Early in your career, the question looks different: an equity investment has more years ahead to make up the loss and aim for a long-term gain, with no certainty and with possible falls along the way.

    Three common situations for internationals in Germany

    You became self-employed. You may have stopped paying into your Riester when you left salaried employment, because you were no longer entitled to subsidies. From 2027, self-employed people with business income or professional income under § 15 or § 18(1) nos. 1 to 3 EStG who have filed a tax return become directly eligible (source: BMF). The question is no longer whether you can be subsidised, but through which contract.

    You are a doctor, dentist, lawyer, architect or notary with a professional pension fund (Versorgungswerk). Compulsory members of a professional pension fund become eligible too. One practical condition: give your fund your consent, by the end of the contribution year at the latest, so that it passes your details to the body that pays the subsidies, the ZfA (source: BMF).

    You are planning to buy your home. Until now, every Riester contract had to allow you to withdraw capital for a home you live in yourself (Wohn-Riester). In the new system, this becomes an option the provider may or may not offer (source: BMF). If you have a property project, check this point before any transfer.

    If you might retire outside the EU

    If you live outside the European Union and the European Economic Area from the start of payments onwards (including if you move away during retirement), you must repay the subsidies and tax benefits received while saving (source: BMF; § 95 EStG). The rule also applies if you live in the EU but are treated as resident outside the EU/EEA under a tax treaty.

    Retiring in another EU or EEA country, such as France, Spain, Italy, the Netherlands or Norway, does not trigger this. Retiring in the UK, Switzerland, the United States, Canada or India does. If retiring outside Europe is a real possibility, take it into account before increasing your payments, whichever subsidy rules you choose.

    Questions to ask yourself before deciding

    • Is your contract worth more or less than your payments plus the subsidies received?
    • How much in subsidies do you receive today, and do you pay in the minimum needed to get them in full?
    • What type of contract do you have (insurance, fund savings plan, bank savings plan), and what does it guarantee?
    • What costs remain if you keep it, and what would a switch cost?
    • At what age do you want to draw on these savings, and how many years away is that?
    • How many children entitle you to child benefit (Kindergeld), and does your spouse also have a contract?
    • Are you planning to buy a property?
    • Where do you expect to live in retirement?

    None of these questions decides on its own: it is the combination that tips the balance towards one of the four options. The answers are in your contract, your annual statement and your subsidy notices.

    Before signing anything in January, take the time to review your situation. At Feller Financial Advisory, I go through your Riester contract with you, in English, French or German, and we compare the options on your actual situation. Book a first conversation

    Frequently asked questions

    Do I have to cancel my Riester contract in 2027? No. Contracts signed before 1 January 2027 can continue under the old subsidy rules (source: BMF).

    What happens if I cancel my Riester to get the money? You repay all the subsidies and tax savings received, and the contract’s gains are taxed (source: BMF; §§ 93 and 22 EStG). Pausing the contract or transferring the capital avoids these consequences.

    Can I transfer my Riester to an Altersvorsorgedepot without losing the subsidies? Yes. You do not repay the subsidies already received, but switching, sales and distribution costs may apply (source: BMF).

    Can I keep my Riester and open an Altersvorsorgedepot as well? Yes, up to two new contracts. But your old contract then loses its protected status and moves to the new subsidy rules (source: BMF).

    How much does transferring my Riester cost? From 2027, your current provider cannot charge anything if your contract is more than five years old, and at most €150 otherwise. The new provider may charge a fee of at most €150, with no acquisition costs on the subsidised capital transferred (sources: AltZertG, § 1, 2027 version; BMF). The notice period is three months to the end of a quarter.

    My contract is at a loss: should I transfer it? Not without thinking it through. The Riester guarantee ensures that at least your contributions will be available when retirement payments start (source: AltZertG, § 1). If you transfer before then, you leave with the current value.

    Can I go back to the old subsidy rules after switching? No, that is not possible (source: BMF).

    What happens if I move outside the EU in retirement? If you live outside the EU/EEA from the start of payments onwards, the subsidies and tax benefits received must be repaid (source: BMF).


  • Altersvorsorgedepot 2027: Full Guide (Grants, Fees, Payout)

    Altersvorsorgedepot 2027: Full Guide (Grants, Fees, Payout)

    Altersvorsorgedepot 2027: the complete guide to Germany’s private pension reform

    Germany’s private pension reform is now law: the Bundestag passed it on 27 March 2026, and the Bundesrat gave its final approval on 8 May 2026. From 1 January 2027, a new state-subsidised retirement savings product enters the German market: the Altersvorsorgedepot (literally, “retirement provision depot”).

    This guide covers what you need to know, factually, before the market opens: who qualifies, how much the state contributes, what fees the law allows, and how you get your capital back at retirement.

    Why this reform?

    The product it replaces, the Riester-Rente, had a well-documented structural flaw: the capital guarantee requirement forced insurers and banks to park a growing share of savers’ money in low-yield bond instruments. In a world of persistently low interest rates followed by high inflation, that guarantee ended up costing more than it protected, crushing return potential over 20-to-40-year horizons.

    That potential comes at a price. Without a guarantee, the value of your depot follows the markets: it can fall, sometimes sharply, including shortly before retirement, and you may get back less than you paid in. Past performance is no guide to future returns. The standard product limits this risk by gradually shifting savings into a cautious fund before retirement (source: BMF).

    Lawmakers made a clear choice: the guarantee is no longer mandatory. You choose between a guaranteed contract (at least 100% or 80% of payments) and a contract without a guarantee, which the law calls the Altersvorsorgedepot. In everyday use, “Altersvorsorgedepot” often refers to the whole new scheme, including the guaranteed versions offered by insurers and fund companies. The version without a guarantee relies on diversification and on equity and ETF markets, with higher return potential over the long term.

    Existing Riester contracts are not disappearing. They keep their grandfathered rights (Bestandsschutz) and continue to run as before. You can also move your contract to the new subsidy rules, or transfer its capital to a new contract without repaying the subsidies already received (source: BMF). The options and their pitfalls are covered in my article on Riester contracts in 2027.

    Who can open an Altersvorsorgedepot?

    This is one of the most significant changes in the reform: the pool of eligible savers is considerably wider than under Riester.

    Eligible for the state grant:

    • employees subject to the statutory pension insurance (gesetzliche Rentenversicherung);
    • civil servants (Beamte), who must consent to their data being passed on;
    • compulsory members of a professional pension fund (Versorgungswerk), such as doctors, lawyers or architects, who must give their fund their consent before the end of the contribution year;
    • and, new under this reform, self-employed people with business income (§ 15 EStG) or professional income (§ 18(1) nos. 1 to 3 EStG) who have filed a tax return, even if they do not pay into the statutory pension scheme (source: BMF).

    This matters for many residents of Germany working as freelancers or in an independent profession. Be careful, however, if you are the managing partner of your own GmbH, usually as majority shareholder (beherrschender Gesellschafter-Geschäftsführer): if you do not pay into the statutory pension insurance, your managing director salary does not entitle you to the grant. A minority managing partner who pays into the statutory scheme remains eligible. Finally, a married spouse with no entitlement of their own can benefit through the other spouse, provided they pay in at least €120 a year; their base grant is then capped at €175 (source: BMF).

    How much to save, how much the state pays

    Contribution thresholds

    • Minimum personal contribution required to qualify for the grant: €120 per year (€10/month).
    • Contribution level that unlocks the maximum grant: €1,800 per year.
    • In total, you can pay in up to €6,840 per year, i.e. €5,040 more than the subsidised band. That part receives neither grant nor tax deduction, but its gains are not taxed during the savings phase (source: BMF).

    The base grant (Grundzulage)

    • 50% grant on the first €360 paid in per year (up to €180);
    • 25% grant on the portion between €360.01 and €1,800 paid in per year (up to a further €360).

    For an annual savings effort of €1,800, the state therefore pays up to €540 in direct grants per year.

    Example with two children:

    Annual paymentBase grantChild grants (2 children)Total grants
    €120 (minimum)€60€240€300
    €300€150€600€750
    €360€180€600€780
    €1,800 (subsidised cap)€540€600€1,140

    Additional bonuses

    • Child bonus (Kinderzulage): for each child who entitles you to child benefit (Kindergeld), the state adds €1 per euro paid in, up to €300 per child, per year.
    • Career-starter bonus (Berufseinsteigerbonus): a one-off bonus of €200 if you are not yet 25 on 1 January of the contribution year.

    Taxation during the savings phase

    Contributions and grants qualify, up to €1,800 of payments plus the grants, for a special-expenses deduction (Sonderausgabenabzug). The tax office automatically calculates whether the direct grant or the tax deduction is more favourable for the taxpayer, and applies whichever result is better. No tax applies to gains or reallocations made inside the depot during the savings phase.

    Three types of contract

    The law provides for three types of subsidised contract (source: BMF).

    • The standard product (Standarddepot): every provider must offer it. It invests in two funds set in advance, one cautious and one more dynamic, with no guarantee. Savings shift automatically into the cautious fund in the years before retirement. Its costs are capped at 1% a year.
    • The flexible Altersvorsorgedepot: no guarantee, with a wider choice of funds or managed portfolios. Its costs are not capped.
    • The guaranteed product (Garantieprodukt): at least 100% or 80% of payments are guaranteed at the start of retirement. Safer, with lower return potential.

    Fees are capped by law: a rare and important feature

    Another notable feature: the law imposes a statutory fee cap on the so-called “standard product”, the baseline offering every provider is legally required to make available.

    • The cap is set at 1% in effective annual costs (Effektivkosten) for this standard product.
    • This cap applies only to the standard product. More elaborate offerings, with a wider fund selection, personalised advice or managed strategies, sit within a broader fee range.
    • The first offers have been presented since autumn 2026. Outside the standard product, fees vary widely from one offer to another, and some also charge a fee on every payment.
    • Acquisition costs must be spread over the whole savings period. After five years, your current provider can no longer charge an exit fee; only the new provider may charge a takeover fee, of at most €150 (source: BMF).

    Over a 30-to-40-year horizon, fee differences between market offers can amount to tens of thousands of euros in final capital. But the headline price is only part of the equation: a self-directed, execution-only account will mechanically show the lowest price, since no advice is included. A contract taken out with an advisor’s support, by contrast, includes an allocation tailored to your horizon and profile, optimisation of your grants and, where relevant, coordination with your tax situation in another country: factors that also weigh on the final outcome, sometimes more than a fraction of a percentage point in fees. The right approach is to compare what is actually included in the price, not just the number on the label.

    How and when you get your capital back

    The payout phase (Auszahlungsphase) follows precise rules:

    • Payouts can start no earlier than age 65, or earlier if you already draw a statutory pension, and must start by age 70 at the latest.
    • Lifelong annuity (Leibrente): a fixed amount paid every month until death. Remaining capital does not pass to your heirs, unless you choose a guaranteed period (10 or 20 years).
    • Drawdown plan (Auszahlungsplan): capital stays invested and is withdrawn gradually; this plan cannot end before the saver’s 85th birthday. Unlike Riester, no part of the capital has to be converted into an annuity at 85. If you die before the plan ends, the remaining capital goes to your heirs, but the grants and tax benefits must then be repaid, unless the capital is transferred to a contract in the surviving spouse’s name (source: BMF).
    • Partial lump sum: up to 30% of the capital can be withdrawn as a single payment at the start of the payout phase, with the remainder paid out as a drawdown plan or a lifelong annuity.
    • Taxation on payout: amounts that come from the subsidised part (drawdown, annuity or lump sum) are taxed as other income (sonstige Einkünfte) at the saver’s personal marginal tax rate, generally lower in retirement than during working life. The part that comes from payments above €1,800 a year is taxed more lightly: for a lifelong annuity, only a portion is taxed (Ertragsanteil); for a drawdown plan or lump sum, only the gains are taxed, under rules that depend on the type of contract (source: BMF; § 22 no. 5 EStG).
    • Moving outside the EU/EEA: if you live outside the European Union and the EEA from the start of payments onwards, you must repay the grants and tax benefits received (source: BMF; § 95 EStG).

    One last thing before you compare offers

    From January 2027, the Altersvorsorgedepot will be sold by providers with different regulatory statuses: banks, insurance companies and tied agents on one side; independent brokers on the other. The former can only offer products from their own house or designated partners; the latter, insurance brokers (Versicherungsmakler, § 34d GewO) or independent financial investment intermediaries (Finanzanlagenvermittler, § 34f GewO), have no capital ties to product providers and can compare the entire market: effective fees, fund universe, quality of the payout structure.

    This distinction explains why two seemingly identical contracts can carry very different fees, since the statutory cap only covers the standard product.

    At Feller Financial Advisory, I help clients navigate this comparison with full independence, in English, French or German. Book an introductory call

    Frequently asked questions

    Who can open an Altersvorsorgedepot? Employees paying into the statutory pension insurance, civil servants and, new for 2027, compulsory members of a Versorgungswerk and self-employed people (business or professional income, tax return filed), even without statutory pension contributions.

    What’s the maximum grant I can receive? Up to €540 per year for a personal contribution of €1,800, plus up to €300 per child and a one-off €200 bonus for savers under 25.

    Is there a legal fee cap? Yes, for the standard product every provider must offer: a maximum of 1% in effective annual costs. More elaborate products, outside the standard scope, can charge more.

    Can an Altersvorsorgedepot lose value? Yes. Without a guarantee, its value follows the markets and can fall, including shortly before retirement. Guaranteed products (100% or 80% of payments) limit this risk, with lower return potential.

    When and how can I access my capital? No earlier than age 65 (earlier if you already draw a statutory pension), as a lifelong annuity, a drawdown plan (which cannot end before age 85), a partial lump-sum withdrawal (up to 30%), or a combination. Payouts are taxed at your personal marginal rate.

    Does my existing Riester contract disappear? No. Existing contracts continue to run under grandfathered rights. You can keep it as it is, move it to the new subsidy rules or transfer its capital without repaying the grants received (source: BMF). The details are in my article on Riester contracts in 2027.

    What happens if I leave Germany? Within the EU or EEA, the contract continues with no repayment. Outside the EU/EEA, it can stay in place during the savings phase, but if you still live there when payments start, the grants and tax benefits must be repaid (source: BMF; § 95 EStG). In both cases, without contributions to the German system, you generally no longer receive new grants.

    When can I actually open one? The scheme takes effect on 1 January 2027. The first offers have been presented since autumn 2026.


  • bAV Germany: The 2026 Guide to Company Pensions

    bAV Germany: The 2026 Guide to Company Pensions

    The German Company Pension Scheme (bAV): Practical Guide 2026

    Understand, optimize, and secure your company pension, with calculation examples, comparisons, and concrete strategies.


    Table of Contents

    1. What is the bAV?
    2. The Leverage Effect of the Employer Match
    3. Taxation During the Accumulation and Payout Phases
    4. The 5 Investment Vehicles (Durchführungswege)
    5. The 3 Pillars: Finding a Balance
    6. Job Changes and Key Pitfalls
    7. Conclusion

    01. What is the bAV?

    The German Pension System: The 3 Pillars

    In Germany, old-age provision officially rests on three complementary pillars. Understanding this architecture is essential to grasp the exact role the bAV plays in your retirement strategy.

    PillarNameFinancingLevel of Coverage
    1st PillarStatutory Pension (GRV)Mandatory contributions employer/employee (50/50)< 50% of average income (declining)
    2nd PillarCompany Pension Scheme (bAV)Employee ± employer matchVariable (depending on contract)
    3rd PillarPrivate Provision (ETF, Real Estate, etc.)Employee aloneVariable, unlimited

    The Principle of Deferred Compensation (Entgeltumwandlung)

    The bAV is based on a simple mechanism: Instead of receiving a portion of your gross salary in cash, you instruct your employer to pay this amount directly into a retirement contract. This amount is deducted before taxes and, up to a certain limit, before social security contributions.

    The Legal Maximum Limits for 2026

    Type of ExemptionMonthly LimitAnnual LimitCalculation Basis
    Tax Exemption (Income Tax)676 €8 112 €8 % BBG (101 400 €)
    Social Security Exemption338 €4 056 €4 % BBG (101 400 €)
    Tax-Free Only Zone (338 € to 676 €)338 €4 056 €No exemption from social security

    (BBG = Beitragsbemessungsgrenze / Contribution Assessment Ceiling of the statutory pension insurance for 2026).

    Practical Tip: Check whether you are affiliated with the statutory health insurance (GKV). If you are privately insured (PKV), the limits for social security exemption apply differently.

    02. The Leverage Effect of the Employer Match

    Practical Example: Thomas, Employee in Munich, €65,000 Gross/Year

    Thomas (35 years old), an engineer at a Bavarian mid-sized company, wants to evaluate the real impact of a bAV contribution of €200/month. His employer offers a 30% match. His marginal tax rate is estimated at 36%. Here is what actually happens:

    ElementWithout bAVWith bAV (€200/month)Impact
    Gross Salary (monthly)5 417 €5 217 €-200 €
    Social Security (~21.75%)-1 178 €-1 134 €+44 €
    Estimated Taxable Income4 239 €4 083 €-156 €
    Income Tax-898 €-837 €+61 €
    Net Salary3 341 €3 246 €-95 €
    Capital Invested in Contract—260 € (incl. 30 % match)+260 €

    Result: Thomas gives up €95 net, but €260 flows into his contract. The immediate leverage effect is more than 2.5x even before any financial return.

    The Break-Even Point: Why Demand 30%?

    The statutory minimum employer match is 15% (mandatory for all deferred compensation contracts since 2022). But beware: This is not a gift from the employer, but the passing on of the social security contributions the company saves. Furthermore, this 15% often just barely covers the insurance costs and does not compensate for the loss of pension points in the statutory pension (Gesetzliche Rente).

    For a bAV contract to beat a private investment in the financial markets, a higher employer contribution is required. Experts agree that the bAV becomes truly advantageous starting at a match of 30%. The following table illustrates this (simulation over 25 years at a 3% annual return in the bAV).

    Employer MatchInvested Capital/MonthbAV Capital (Gross after
    25 yrs at 3%)
    Actual bAV Value (Estimated NET after taxes)Required Savings Rate (at 6%) to match this Net
    0 %200 €89 201 €≈ 66 900 €~ 96 €
    15 %230 €102 581 €≈ 76 900 €~ 111 €
    30 %260 €115 962 €≈ 86 900 €~ 125 €
    50 %300 €133 802 €≈ 100 300 €~ 145 €

    The column ‘Required Savings Rate‘ indicates the amount you would need to invest out of pocket every month into a private investment (e.g., an ETF/Fund at 6% p.a.) to achieve the same net capital.

    How to Evaluate Your Employer’s Offer?

    The percentage of the employer match is the main criterion for judging whether a bAV contract is worthwhile:

    • 0 % : The initial tax savings are neutralized by deferred taxation in retirement and the insurer’s fees. Ultimately, this yields no more than a private investment, but carries the major disadvantage of locking up your money until age 62.
    • 15 % : This statutory minimum gives you only a slight mathematical advantage over a private investment (equivalent to about €16 of additional profit per month). You have to weigh whether this small bonus justifies locking away your money for decades.
    • 30 % : From this level onwards, the employer’s assistance generously covers all future taxes and fees. By paying €95 out of pocket, you get the same value as if you had saved €125 privately. Locking up the capital until retirement becomes highly attractive here.
    • 50 % (and more): With such strong support, your employer finances a large part of your future pension. Your personal savings effort is leveraged so heavily that this contract becomes far more advantageous than almost any traditional private investment.

    03. Taxation During the Accumulation and Payout Phases

    Phase 1) During the Accumulation Phase: The Immediate Tax Advantage

    During the build-up phase, contributions are, as mentioned above, exempt from income tax (up to 8% of the BBG) and social security contributions (up to 4% of the BBG).

    Phase 2) In Retirement: Deferred Taxation (nachgelagerte Besteuerung)

    The benefits from the bAV are fully taxable upon payout. Three types of deductions apply:

    DeductionEstimated RateCalculation BasisNote
    Income Tax (ESt)Marginal tax rate in retirement (often 20–30%)Entire pension or capitalThe tax rate in retirement is usually lower than during working life.
    Health Insurance (KV)~14.6% + Additional Contribution (Total ~16-17%)Only on the portion exceeding €197.75/month (Freibetrag)Applies only to statutory insured (GKV). Privately insured (PKV) do not pay KV/PV on the bAV. The allowance (Freibetrag) protects the first €197.75.
    Long-Term Care Insurance (PV)~3.4% to 4% (depending on children)On the entire pension if it exceeds €197.75/month (Freigrenze)No deduction if the limit is exceeded; full contributions apply from the first euro. Applies only in GKV.
    Solidarity Surcharge (Soli)5.5% of Income TaxCalculated Income TaxFull exemption if the annual income tax due is below €20,350 (single) or €40,700 (married). Exempts the vast majority of retirees.

    Calculation Example: Monthly bAV Pension of €400 (GKV Member)

    Thanks to the statutory allowance of €197.75 in 2026, health insurance is only due on the exceeding amount:

    • Gross Pension : 400 €
    • Income Tax (estimated 22%) : -88 €
    • Health Insurance (KV ~ 16.3%): – 33 € (Thanks to the allowance, applies only to the difference: €400 – €197.75 = €202.25)
    • Long-Term Care Insurance (PV ~ 3.4%) : – 14 € (Calculated on the full €400, since the pension exceeds the exemption limit of €197.75)
    • Net Pension Paid Out: 265 € (equivalent to approx. 66% of the gross amount)

    A retiree with private health insurance (PKV) bypasses the KV/PV contributions; their net pension in this example would be approx. €312.

    04. The 5 Investment Vehicles (Durchführungswege)

    Unlike a private savings plan where you freely choose your bank, with the bAV, the company decides on the provider and the legal framework (Durchführungsweg). There are five options:

    • Direct Insurance (Direktversicherung): The absolute standard and the most widespread vehicle. The employer takes out a classic life or pension insurance policy on your behalf. This option is the easiest to transfer when changing jobs.
    • Pension Fund (Pensionskasse): A legally independent pension institution, often for specific industries. Returns are moderate but very stable, a good choice for employees who plan to stay with the same company long-term.
    • Pension Fund (Pensionsfonds): The most dynamic option. It allows for a higher exposure to the stock market to boost returns, though it entails higher volatility. Particularly suitable for employees with a long investment horizon.
    • Support Fund (Unterstützungskasse): The preferred instrument for executives and high earners. The main advantage: There are no legal maximum limits for contributions, meaning far higher amounts can be deferred tax-free than with standard vehicles.
    • Direct Commitment (Direktzusage / Pensionszusage): The most binding model for the company, which provisions your future pension directly as a liability on its own balance sheet. Offers maximum tax advantages but is mostly reserved for large companies and managing directors.

    05. The 3 Pillars: Finding a Balance

    Where does the bAV fit into your overall strategy?

    The bAV should not be viewed in isolation: Its full value only becomes apparent when compared to the other two pillars. Each has its own strengths and limitations.

    Criterion1st Pillar: Statutory Pension2nd Pillar: bAV3rd Pillar: Private Provision
    FinancingMandatory contributions employer/employeeDeferred compensation & employer matchVoluntary individual effort
    Tax AdvantageDeductible up to €30,826/yearTax-free up to €676/month, SS-free up to €338/monthDepends on the product (Riester, Rürup, Brokerage…)
    Expected ReturnLinked to wage growth and demographics1.5% – >5% depending on investmentVariable depending on asset allocation
    LiquidityNone (Payout from age 63–67)None (Payout from age 62)Completely flexible (except Rürup/Riester)
    Level of Coverage< 50% of average income (declining)Variable addition based on personal contributionUnlimited, depends on savings rate

    Important: No pillar can stand alone. The first forms the guaranteed foundation, the bAV optimizes this through tax advantages and employer subsidies, and the third pillar provides the absolute flexibility that the other two lack. It is their interplay that makes your strategy robust.

    06. Job Changes and Key Pitfalls

    What happens if I change employers?

    ScenarioLegal BasisWhat happens?Recommendation
    Transfer to the new employerLegal right to capital transferThe capital moves to the new bAV. Warning: The new insurer often charges new acquisition costs.Carefully compare costs before transferring.
    Pausing Contributions (Beitragsfreistellung)Absolute legal right (§ 1a BetrAVG).The contract is “frozen.” You stop paying in, but the existing capital continues to grow until retirement.When changing jobs, this is very often the best option to avoid paying commission fees twice.
    Early Payout (Abfindung)Prohibited before age 62Since the Company Pension Strengthening Act II (2026), the employer may pay out the contract without your consent if its value is below €7,119.The paid-out capital will be heavily taxed by income tax in that year.

    Vesting: When do the employer contributions truly belong to you?

    Since 2018, the rights to employer contributions are legally vested (Unverfallbarkeit) as soon as the contract has existed for 3 years and you have reached the age of 21. If you leave the company before that, you may lose the accumulated match.

    ⚠ Warning: Never sign a bAV transfer into a new contract without comparing the acquisition and distribution costs. A contract with a 4% acquisition fee can wipe out several years of tax benefits.

    07. Conclusion

    The bAV is a precise instrument: Poorly configured, it disappoints; optimally adjusted, it shines. Before signing the offer from your HR department or making a decision during a job change, a strict review is essential:

    1. The Employer Match: Is it above the 30% threshold? If not, a detailed mathematical analysis is strictly required.

    2. Cost Analysis: A contract with a 4% acquisition fee eats up your tax advantages. Examine the provider’s cost structure closely.

    3. Choice of Investment Vehicle: Does the proposed model (usually Direct Insurance) truly fit your tax bracket and investment horizon?

    4. The Pension Gap: Use the projections from the German Statutory Pension Insurance to calculate the impact of deferred compensation on your state pension.

    5. GKV vs. PKV: Take into account the massive impact your health insurance status will have on the later net return of your bAV.

    6. Pension vs. Capital Payout: Does your contract offer a flexible payout? It is important to compare the tax consequences of both scenarios in advance.

    7. Your Overall Asset Allocation: No contract replaces a liquid financial cushion. Balance your savings rate between the locked-in bAV and freely available private investments.

    Let us analyze your contract

    The bAV is an extremely powerful tool, provided it is set up correctly. An independent review of your contract ensures that the match is sufficient, no hidden costs are lurking, the right investment vehicle was chosen, and taxation in old age is optimized.

    Contact us for a personalized analysis of your individual situation.


    Disclaimer: This practical guide is for informational and educational purposes only and does not constitute personalized financial advice. All figures and exemption limits are based on the applicable German legislation of the year 2026. Consult an independent advisor for an analysis tailored to your personal situation.

  • The €668k Cost of Early Retirement in Germany for Executives

    The €668k Cost of Early Retirement in Germany for Executives

    The cost of time: understanding the €668,000 opportunity cost of early retirement in Germany

    For corporate executives and high-net-worth professionals in Germany, the decision to retire at 63 is rarely driven by financial necessity. It is a prioritisation of temporal autonomy. The Rente mit 63 is a well-established social concept, but executing this transition without a precise, well-thought financial architecture exposes the individual to a significant, often unrecognised, capital reduction.

    As the German state manages a shifting demographic landscape, specifically, the narrowing ratio of active contributors to beneficiaries, the Deutsche Rentenversicherung relies on the principle of actuarial neutrality. The statutory system is structurally designed to penalise early exits to ensure the state’s long-term liabilities remain balanced.

    For the affluent professional, retiring at 63 without a bespoke mitigation strategy triggers a compounding reduction in lifetime wealth that our models place at ~€668,000. This article aims to precise how this wealth reduction arises.

    I. The mechanics of the state pension

    The German statutory pension is not a percentage of your final salary. It is a defined-contribution system denominated in a proprietary currency: the Entgeltpunkt (pension point / EP). Every year, your annual gross salary is divided by a benchmark salary, giving you a defined amoutn of pension points.

    Your gross monthly pension is determined by four variables: your lifetime accumulated points (Entgeltpunkte), multiplied by the access factor (Zugangsfaktor), the pension type factor (Rentenartfaktor), and the current monetary value of a single point (Aktueller Rentenwert).

    For high earners, point accumulation is constrained by two statutory ceilings:

    Parameter2026 ValueImplication
    Durchschnittsentgelt (average benchmark)€51,944Earning this yields exactly 1.00 EP per year
    Beitragsbemessungsgrenze (contribution ceiling)€101,400Income above this is invisible to the system
    Maximum annual accumulation1.95 EP (€101,400/€51,944)Absolute ceiling
    Aktueller Rentenwert (point value, Jan 2026)€40.79Rising to €42.52 from July 2026

    Income above €101,400 generates no additional pension entitlement whatsoever. The pension does not scale with professional success beyond this ceiling and this constraint, combined with the penalty mechanism described below, is where the actuarial mathematics begin to work decisively against the early retiree.

    II. The executive trajectory: a quantitative case study

    To illustrate the financial impact, we analyse “Alex,” a 40-year-old senior executive. His career trajectory maps as follows: he entered the workforce at 25 and has accumulated 15 points over his first fifteen years (earning the benchmark salary on average). Between ages 40 and 55, he averages 1.5 points per year adding 22.5 points to reach a total of 37.5 by age 55. After 55, with gross income exceeding €10,000 per month, he hits the statutory ceiling and earns the maximum 1.95 points annually.

    At 55, Alex has two possibilities:

    MetricScenario A: Retire at 63Scenario B: Retire at 67
    Remaining active years (from age 55)8 years12 years
    Points yield in final phase15.6 (8 × 1.95)23.4 (12 × 1.95)
    Total lifetime accumulation53.1 points60.9 points
    Zugangsfaktor (access factor)0.856 (permanent 14.4% penalty)1.000 (no penalty)

    III. Projecting the financial reality: the €1,075 monthly gap

    To understand what each scenario actually delivers, we project the Aktueller Rentenwert (value of one pension point) forward at a conservative 2% annual growth rate consistent with its historical wage-indexation trajectory. Starting from the January 2026 baseline of €40.79, the point value reaches approximately €64.32 by the time Alex turns 63 (in 23 years), and €69.62 by 67 (in 27 years).

    Applying these projected values to each scenario:

    • Scenario A: 53.1 points × €64.32 × 0.856 = €2,923 gross per month at age 63
    • Scenario B: 60.9 points × €69.62 × 1.000 = €4,239 gross per month at age 67

    To compare both scenarios at the same age, we apply 2% annual indexation to Alex’s early pension from 63 to 67. By age 67, his Scenario A pension will have grown to approximately €3,164 per month. Against Scenario B’s starting pension of €4,239, the result is a permanent structural shortfall of €1,075 every single month.

    Crucially, this gap is not static. Because both pensions are indexed at the same rate, the euro-value of the shortfall increases over time. By age 87, the monthly deficit will have widened to nearly €1,597. This is the compounding nature of the actuarial penalty and the reason a single snapshot figure understates the true lifetime exposure.

    IV. The triple penalty: anatomy of the €668,137 gap

    Assuming a life expectancy to age 87, three mechanisms operate independently and in parallel. This analysis is conducted gross-to-gross throughout, excluding individual tax assumptions, to ensure the figures are transparent and auditable regardless of personal marginal rate.

    1. The gross transition deficit (ages 63 to 67)

    Between ages 63 and 67, Alex stops earning his peak salary of €10,000 gross per month, forfeiting €480,000 in gross income over four years. During this same period, he collects his early pension, approximately €144,602 gross over those 48 months. The direct gross cash flow deficit during this transition is €335,398.

    2. The forfeiture of peak points (ages 67 to 87)

    By stopping at 63, Alex permanently forgoes 7.8 points: those that would have been earned in the final four years at the maximum accumulation rate. These are mathematically the most valuable points of his career, contributing disproportionately to his total lifetime accumulation compared to his earlier working years. Projected over a 20-year retirement with 2% annual indexation, their absence costs €168,024 in gross pension income.

    3. The contagion effect (ages 67 to 87)

    The Zugangsfaktor mandates a 0.3% deduction for every month of early retirement. At 48 months, this produces a 14.4% permanent discount, applied not to the missing points alone, but retroactively to every point Alex has ever accumulated, from the first day of his first job. Over 20 years of retirement, this additional drag costs €164,715 in gross pension income.

    Source of erosionDriverGross impact
    Transition deficit (ages 63–67)€480,000 foregone salary minus €144,602 pension collected€335,398
    Missing peak points (ages 67–87)7.8 forfeited points × indexed point value€168,024
    Early-retirement discount (ages 67–87)14.4% permanent ZF penalty on 53.1 accumulated points€164,715
    Total lifetime wealth reduction€668,137

    Executing an early retirement without an offsetting capital strategy represents a substantial, unrecoverable reduction in lifetime wealth.

    V. The three headwinds your pension letter does not mention

    The standard annual Renteninformation from the Deutsche Rentenversicherung is designed for average earners in straightforward circumstances. For the high-net-worth professional, it is dangerously incomplete. Three structural complexities are systematically absent from every public planning tool.

    The first is the hidden offset mechanism. The standard statement clearly outlines the permanent penalty for early retirement, but it fails to mention your statutory right to erase it. Starting at age 50, you can make voluntary payments (Ausgleichszahlungen) to “buy back” these missing points. For high earners, spreading these contributions across peak-earning years generates substantial tax deductions. This allows you to effectively use current tax savings to help fund your early exit, a major strategic advantage that generic projections completely ignore.

    The second is healthcare friction. Early retirement fundamentally restructures how health insurance premiums are calculated and subsidised, whether you hold private insurance (PKV) or voluntary statutory coverage (freiwillig GKV). The transition to retirement changes your premium basis in ways that can consume your net monthly liquidity. A silent drag compounding over a multi-decade retirement horizon.

    The third is the inflation illusion. The statutory pension is indexed to average wages, not to your personal cost of living. If your bridge capital is allocated to conservative, low-yield instruments, its real purchasing power will erode materially before age 70. Any credible bridge strategy must be engineered to outpace both headline inflation and the natural spending drift of a high-expenditure retirement.

    Bridging a gap of this magnitude requires a structured financial plan, not generic savings advice. The solution typically focuses on funding tax-advantaged private pensions and building inflation-resistant income streams such as real estate to replace your lost salary. How and which of these instruments are combined depends entirely on your tax situation, your existing portfolio, and your personal timeline.

    Conclusion: engineering your exit

    Germany’s statutory system rewards patience and taxes impatience at scale. For the successful professional, however, trading capital for time is often the ultimate objective and it is entirely achievable when the structural groundwork is laid in advance.

    The question is not whether you can afford to retire at 63. It is whether you know the euro-precise magnitude of your personal exposure, and whether the mechanisms necessary to neutralise it are already in motion this fiscal year.

    Every executive’s financial architecture is unique, governed by specific tax situations, existing asset allocations, and long-term legacy goals. Standardised advice leaves substantial capital exposed to structural inefficiencies that compound silently over decades.

  • The Retirement Gap in Germany: How It Hits High-Income Professionals

    The Retirement Gap in Germany: How It Hits High-Income Professionals

    The Income Cliff: Why High Earners in Germany Face the Steepest Retirement Drop

    If you’re earning a six-figure salary in Germany, you’re likely operating under a dangerous assumption: that the statutory pension system (Gesetzliche Rentenversicherung) scales proportionally with your income.

    It doesn’t.

    The German pension system is structurally designed to cap benefits, creating what we call the Replacement Rate Paradox. While an average earner might retain 48% of their net income in retirement, a high earner could see that figure plummet to 15% or less, not due to poor planning, but by design.

    The entire problem stems from the Beitragsbemessungsgrenze (BBG): the Contribution Assessment Ceiling. In 2025, this ceiling sits at approximately €96,600 annually.

    Here’s what this means in practice:

    • Earning €80,000? You contribute on the full €80,000.
    • Earning €150,000? You still only contribute on ~€96,600.

    Every euro earned above this threshold generates zero additional statutory pension entitlement. Your contributions max out at a level designed for upper-middle-class earners, not executive compensation.

    This isn’t a loophole to exploit, it’s a ceiling that creates a structural retirement deficit for anyone substantially above it.

    The Lifestyle Gap: Running the Numbers

    Let’s make this concrete with a real-world scenario.

    Your current situation:

    • Monthly household expenses: €6,500 (housing, international travel, private education, discretionary spending)
    • Annual gross income: €150,000
    • Years until retirement: 20

    Your projected statutory pension: Even with a perfect 45-year German contribution history, the maximum statutory pension based on the BBG cap is approximately €3,500 gross monthly. After mandatory health insurance contributions and progressive taxation (which increasingly applies to pensioners), your net figure drops to roughly €2,500 per month.

    The gap: €6,500 (lifestyle requirement) – €2,500 (pension) = €4,000 monthly shortfall

    To fund a €4,000 monthly gap for 25 years of retirement, accounting for 3% inflation and conservative 4% real returns, you need approximately €1 million in liquid net assets at retirement age.

    This isn’t discretionary savings, this is a structural liability that requires dedicated capital allocation.

    The challenge compounds for international executives and professionals. The German pension calculation rewards contribution continuity. If your career includes periods in the UK, US, Singapore, or other markets before relocating to Germany, your German contribution record is shorter.

    While EU social security treaties help aggregate contribution periods for eligibility, they don’t increase the value of your German pension points. Your entitlement will likely fall well below the theoretical maximum, widening the retirement gap even further.

    For many of our international clients, the practical statutory pension figure is closer to €1,500–€1,800 net monthly, making the gap even more acute, with low or negative correlations, demonstrating the quantifiable benefit of true diversification.

    Most generic financial guidance centers on simple accumulation: “Save 15% of your income in a diversified ETF portfolio.”

    For high earners in Germany, this approach is both insufficient and tax-inefficient. Here’s why:

    1. You’re saving with net income, not gross In the 42% or 45% tax bracket, every euro you invest has already been taxed. The immediate value destruction is substantial.

    2. The gap requires precision, not accumulation You’re not building wealth from zero, you’re solving a specific liability: bridging a quantified monthly shortfall for a defined period. This is an Asset-Liability Matching problem, not a growth optimization problem.

    3. Time horizon allows for structural advantages With 15+ years to retirement, holding excessive daily liquidity in standard equities carries a significant opportunity cost. You can capture premiums that aren’t available to shorter-term investors.

    Closing a retirement gap of this magnitude requires three structural pillars:

    1. Tax-Leveraged Accumulation

    Deploy capital before taxation wherever possible. In a 42%–45% marginal bracket, the immediate return from tax deferral often exceeds what you’d earn from market alpha. Certain German-compliant structures allow you to invest gross income, creating compounding advantages that dwarf standard after-tax investing.

    2. Capturing the Illiquidity Premium

    Your capital has a 15–25 year lock-up horizon, most high earners hold too much unnecessary liquidity. Allocating a strategic portion to private markets (Private Equity, Infrastructure, Real Estate) allows you to capture the illiquidity premium: the additional 2–4% annual return compensated for longer commitment periods. Over two decades, this difference is transformational.

    3. Strategic Geographic Diversification

    Your retirement income shouldn’t depend entirely on a single jurisdiction’s tax regime or currency. High earners often face the risk of “tax regime shift”: changes in German tax policy that could erode purchasing power decades from now. Building income streams across multiple jurisdictions (whether through international real estate, or multi-currency portfolios) creates both tax optionality and political risk mitigation. When you retire, you’ll have the flexibility to optimize withdrawal strategies based on the most favorable tax treatment available at that time, rather than being locked into a single system.

    High income does not equal high retirement income in Germany. The statutory system wasn’t designed for your compensation level, and standard advice wasn’t designed for your tax situation.

    The Income Cliff is mathematically inevitable, but it’s also solvable with precision planning and the right structural approach.

    We conduct comprehensive Pension Gap Analysis for high earners: a detailed calculation of your projected statutory entitlement versus your actual liquidity requirements, along with a tax-optimized roadmap to bridge the difference.

    If you’d like to see your specific numbers and explore a solution designed for your situation, reach out for a confidential consultation.


    Important Disclaimer: This article provides general information and does not constitute personalized financial advice. Individual circumstances vary significantly, and any financial strategy should be developed in consultation with a qualified advisor familiar with your complete situation.